IIFCL, Mahanadi Coalfields and South Eastern Coalfields in Listing Pipeline; Second Public InvIT Also Planned
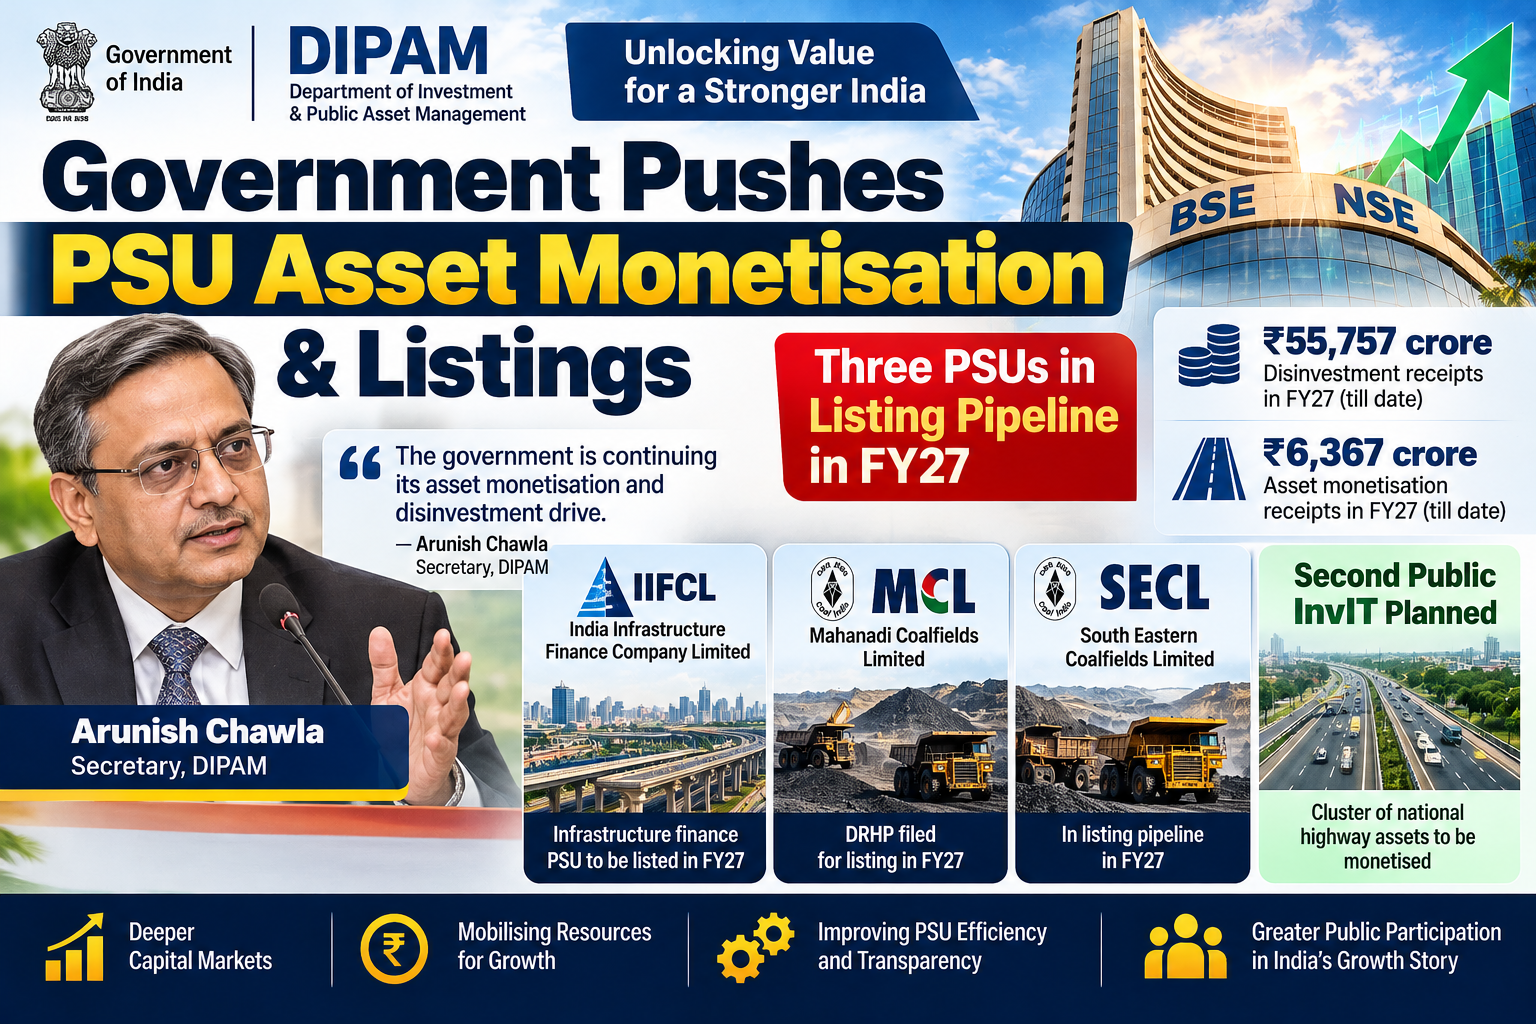
New Delhi, October 26, 2026: The Government of India is stepping up its public-sector asset monetisation and disinvestment programme, with three major public-sector enterprises being prepared for stock-market listing during the current financial year. India Infrastructure Finance Company Limited (IIFCL), Mahanadi Coalfields Limited (MCL) and South Eastern Coalfields Limited (SECL) are among the key companies identified for listing in FY27, according to Department of Investment and Public Asset Management (DIPAM) Secretary Arunish Chawla.
The proposed listings are part of a broader strategy to unlock value from public-sector assets, deepen capital-market participation and mobilise additional resources for the government and the wider economy. The move comes after a significant year of offer-for-sale transactions and other disinvestment measures involving listed public-sector companies.
Three Major PSUs in the FY27 Listing Pipeline
The proposed listing programme covers three companies with distinctly different business profiles.
IIFCL, a wholly owned Government of India company established in 2006, provides long-term financial assistance to viable infrastructure projects. Its proposed public offering would provide investors exposure to India’s infrastructure-financing ecosystem while also creating a market-based valuation for the government-owned institution.
Mahanadi Coalfields Limited, a subsidiary of Coal India Limited, is one of India’s major coal-producing companies. It operates mines in Odisha, including the Talcher and Ib Valley coalfields. MCL has already moved ahead in the listing process, with its Draft Red Herring Prospectus (DRHP) filed, making it the most advanced among the three proposed listings.
South Eastern Coalfields Limited, another major Coal India subsidiary, is also being prepared for listing. SECL is a significant contributor to India’s coal production and plays an important role in meeting the country’s energy requirements.
According to Chawla, preparations for IIFCL and SECL are also underway and the three companies are considered market-ready for the proposed FY27 listings.
Government’s Disinvestment Momentum
The planned IPOs come against the backdrop of strong mobilisation through disinvestment and asset monetisation during FY27.
According to the official DIPAM dashboard, the government has recorded ₹55,757.29 crore in disinvestment receipts and ₹6,366.93 crore through asset monetisation during FY27, taking the combined amount from these two categories to more than ₹62,000 crore.
Major transactions during the year have included stake sales in companies such as Life Insurance Corporation of India, Coal India, Central Bank of India, NHPC, NLC India, Indian Railway Finance Corporation, Cochin Shipyard and Hindustan Copper.
DIPAM’s approach reflects a broader shift from viewing disinvestment simply as a source of government revenue towards using capital markets to improve efficiency, transparency and value discovery in public-sector enterprises.
IIFCL Listing Has Strategic Importance
The proposed IIFCL listing is particularly significant because the company occupies an important position in India’s infrastructure-financing architecture.
IIFCL supports infrastructure projects across areas such as roads, power and other strategic infrastructure. Its public listing could provide greater visibility to the institution, introduce market discipline and potentially broaden its access to capital markets.
For the government, IIFCL is also different from the proposed Coal India subsidiary listings in terms of the flow of proceeds. As the government is the sole shareholder of IIFCL, proceeds from an IPO would accrue directly to the government. In contrast, stake-sale proceeds from MCL and SECL would accrue to their parent company, Coal India, with the government benefiting indirectly through its ownership in Coal India and potential dividend flows.
Second Public InvIT Planned
The government’s asset monetisation programme is not limited to PSU listings.
DIPAM is also working on a second public Infrastructure Investment Trust (InvIT), with a cluster of national highway stretches identified as the underlying assets. The proposed structure is intended to monetise future revenue streams from operational infrastructure without selling the underlying assets outright.
This model is effectively a form of capital recycling. Existing infrastructure assets generate predictable future cash flows, which can be packaged into an investment vehicle and offered to investors. The proceeds can then support the creation of new infrastructure assets.
The government’s maiden public InvIT, launched in March 2026, raised approximately ₹9,200 crore, according to recent reports. The proposed second InvIT is expected to build on that experience and further expand the role of capital markets in infrastructure financing.
Beyond Revenue: Unlocking Public-Sector Value
The FY27 programme indicates that the government is seeking more than immediate fiscal receipts. Listing large and strategically important PSUs can improve corporate governance, enhance transparency, create independent market valuations and widen public participation in India’s growth story.
For investors, the proposed listings could provide access to businesses spanning infrastructure finance and coal production. For the companies themselves, a public listing can increase visibility and potentially create a broader platform for future capital-market transactions.
At the same time, the government has indicated that every asset will be evaluated individually rather than applying a uniform monetisation strategy. Market conditions, valuation, strategic importance and the potential to maximise value are expected to influence the timing and structure of transactions.
A Broader Disinvestment Roadmap
The government is also continuing to examine further stake sales in listed public-sector companies and gradual reduction of government ownership in public-sector banks where applicable. DIPAM has indicated that additional transactions could be considered depending on market conditions and the merits of individual assets.
This approach suggests that FY27 could see a combination of new PSU listings, offer-for-sale transactions, strategic disinvestment and infrastructure monetisation rather than dependence on a single method.
Outlook
The proposed listings of IIFCL, MCL and SECL represent an important development in India’s evolving public-sector capital-market strategy. While the exact issue sizes, pricing, timelines and final regulatory approvals remain subject to the respective processes, the government’s intention to bring three sizeable public-sector enterprises to the market marks a significant expansion of the FY27 listing pipeline.
For the broader economy, the programme could help mobilise long-term capital, strengthen infrastructure financing and improve value discovery in government-owned enterprises.
The combination of PSU listings, asset monetisation, OFS transactions and InvITs indicates that the government’s disinvestment strategy is increasingly becoming a broader capital-recycling exercise—aimed not merely at raising funds, but at unlocking the value of existing public assets and directing capital towards India’s next phase of infrastructure and economic growth.
The Worldonomics Times | PSU & Economy Desk