MCA Extends Due Dates for AOC-4 and MGT-7 for FY 2025–26: Key Compliance Update for Companies
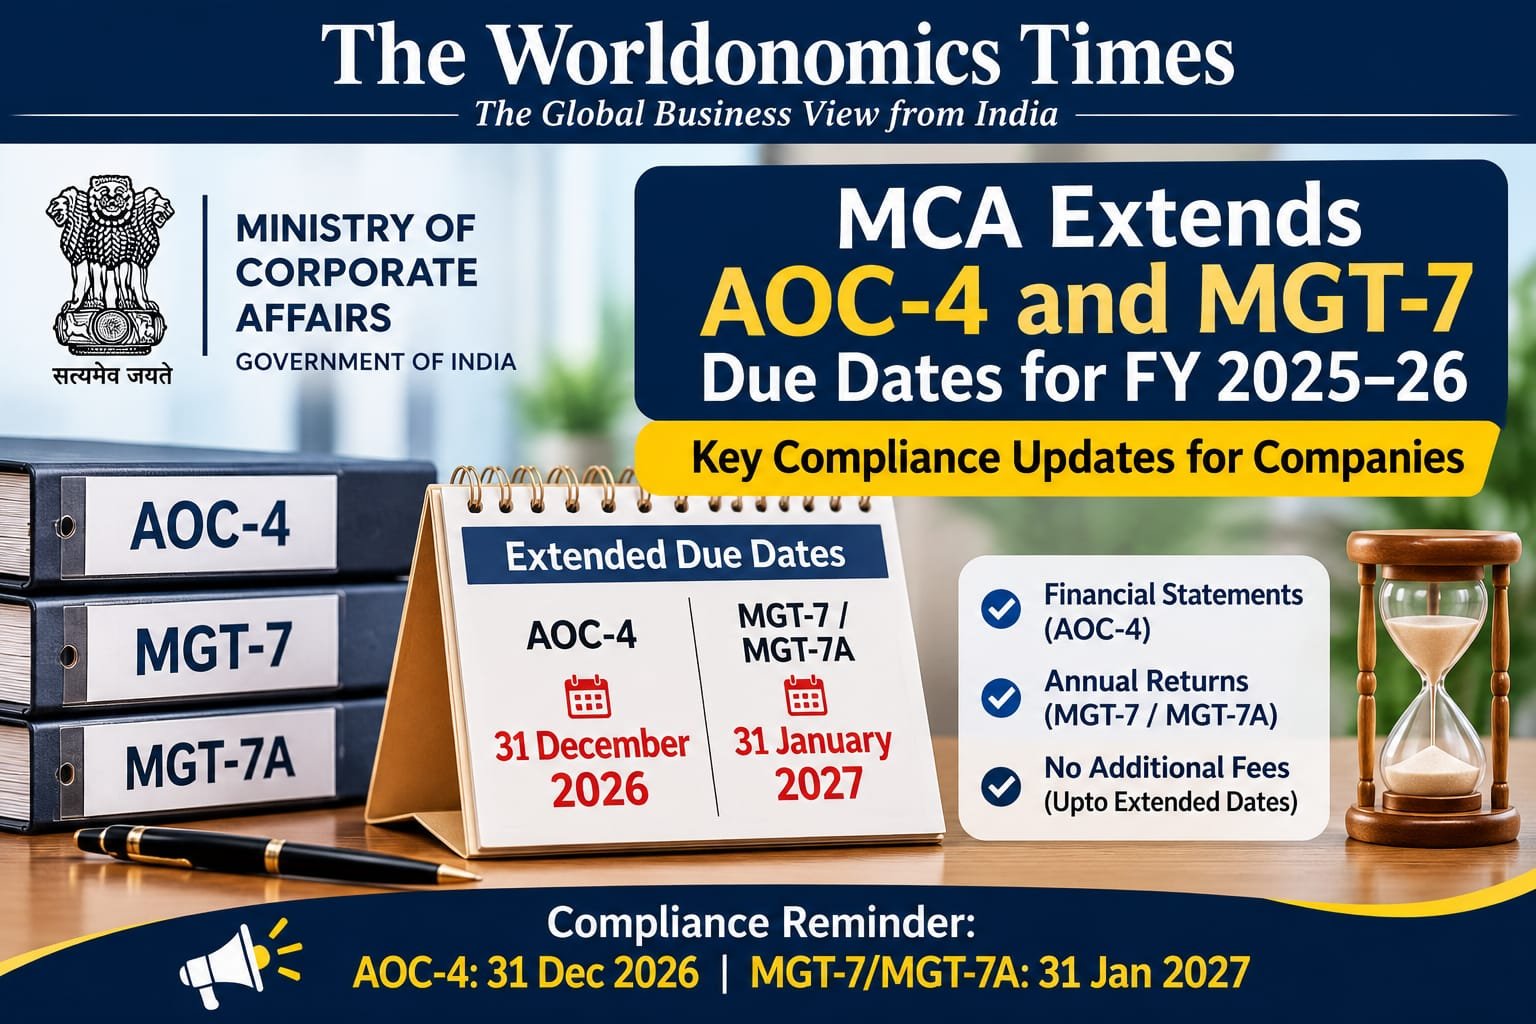
The Ministry of Corporate Affairs (MCA) has provided relief to companies by extending the timeline for filing financial statements and annual returns for the financial year 2025–26, without payment of additional fees.
Through General Circular No. 05/2026 dated 24 October 2026, the MCA has allowed companies additional time to complete their annual filing compliances under the Companies Act, 2013.
- Extended Due Dates at a Glance
E-Form| Purpose| Extended Due Date
AOC-4 and applicable variants| Filing of financial statements| 31 December 2026
MGT-7 / MGT-7A| Filing of annual return| 31 January 2027
These extended dates apply to filings relating to FY 2025–26 and are available without payment of additional fees.
- What is Form AOC-4?
Form AOC-4 is used by companies to file their financial statements with the Registrar of Companies (ROC), as required under Section 137 of the Companies Act, 2013.
It generally includes the financial statements along with relevant attachments, such as the Board’s Report and Auditor’s Report, as applicable.
Normal statutory due date: Within 30 days of the date of the Annual General Meeting (AGM).
For FY 2025–26, where the AGM is held on 30 September 2026, the normal due date for filing AOC-4 would be 30 October 2026. However, under the MCA’s relaxation, the form can be filed up to 31 December 2026 without additional fees.
- What is Form MGT-7 / MGT-7A?
Form MGT-7 is the annual return filed by a company with the ROC under Section 92 of the Companies Act, 2013.
It contains important information relating to the company’s registered office, principal business activities, shareholding pattern, indebtedness, directors and key managerial personnel, and other prescribed particulars.
Eligible One Person Companies (OPCs) and small companies file the abridged annual return in Form MGT-7A.
Normal statutory due date: Within 60 days from the date of the AGM.
For an AGM held on 30 September 2026, the normal due date would be 29 November 2026. Under General Circular No. 05/2026, MGT-7 and MGT-7A can be filed up to 31 January 2027 without additional fees.
- Important Clarification: AGM Deadline Has Not Been Extended
One important point companies must understand is that the MCA has extended the filing timeline only for the specified financial statements and annual returns.
The circular does not extend the statutory timeline for holding the AGM. Companies must continue to comply with the AGM requirements under Section 96 of the Companies Act, 2013.
Therefore, relaxation in filing deadlines should not be treated as relaxation from holding the AGM within the prescribed period.
- What Happens If the Extended Due Dates Are Missed?
Companies filing the applicable forms after the relaxed dates will be liable to pay additional fees as prescribed under the Companies Act and the Companies (Registration Offices and Fees) Rules, 2014.
Importantly, the additional fees will be calculated from the original statutory due date and not from the extended date.
The relaxation is limited to additional fees. Applicable normal filing fees will continue to apply.
Conclusion
The MCA’s General Circular No. 05/2026 provides useful relief to companies and professionals by allowing additional time to complete annual filing compliances for FY 2025–26.
Companies should use this extended timeline effectively and ensure that their financial statements and annual returns are properly prepared and filed within the prescribed dates.
Compliance Reminder:
- AOC-4: 31 December 2026
- MGT-7 / MGT-7A: 31 January 2027
Timely filing remains essential for maintaining statutory compliance and avoiding additional financial liabilities.