By: The Worldonomics Times
Introduction
NMDC Limited, India’s largest iron ore producer and a Navratna Central Public Sector Enterprise (CPSE) under the Ministry of Steel, has reported a strong operational performance for the second quarter (Q2) and first half (H1) of the financial year 2026-27.
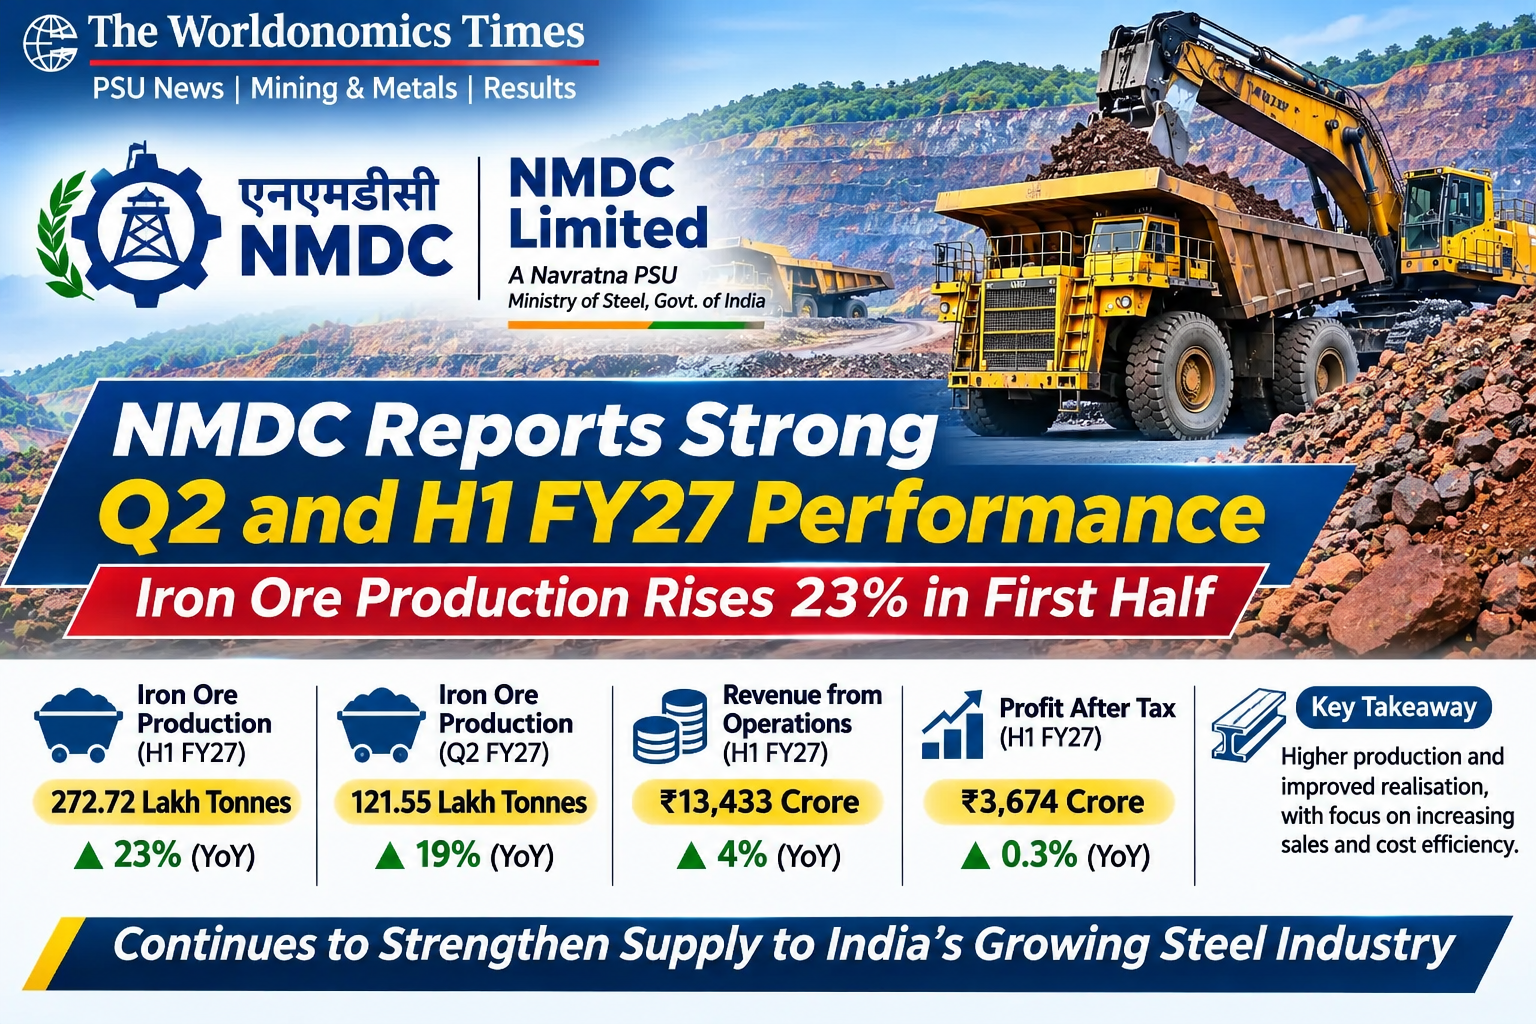
The company recorded a 23% year-on-year increase in iron ore production during the first six months of FY27, reaching 272.72 lakh tonnes (27.27 million tonnes), compared with 222.02 lakh tonnes in the corresponding period of the previous financial year.
The company also achieved record half-yearly revenue from operations of ₹13,433 crore, registering growth of approximately 4% over ₹12,895 crore reported in H1 FY26.
The performance reflects NMDC’s continued focus on increasing mining output, improving operational efficiency and meeting the growing raw material requirements of India’s steel industry.
However, the financial results also highlight a difference between production growth and sales growth, with higher operating expenses limiting the improvement in profitability.
H1 FY27: Iron Ore Production Jumps 23%
One of the most significant highlights of NMDC’s performance is its substantial increase in iron ore production.
During H1 FY27, the company produced 272.72 lakh tonnes of iron ore, compared with 222.02 lakh tonnes during H1 FY26, registering a growth of 23%.
The first-half production figure represents a record performance for the company.
The major operational highlights include:
- Iron ore production: 272.72 lakh tonnes, up 23%.
- Iron ore sales: 222.13 lakh tonnes, broadly unchanged from 222.33 lakh tonnes.
- Ore transferred for pellet production: 19.65 lakh tonnes, up 43%.
- Average domestic iron ore realisation: ₹5,520 per tonne, up 7%.
The difference between production and sales growth is an important aspect of the company’s operational performance. While output increased substantially, sales remained almost unchanged during the first half.
This indicates that increased production has not yet translated into a corresponding rise in sales volumes, making inventory management, logistics and market demand important factors to monitor.
Q2 FY27: Production Increases 19%
NMDC also reported encouraging operational growth during the second quarter of FY27.
Iron ore production reached 121.55 lakh tonnes in Q2 FY27, compared with 102.08 lakh tonnes in the corresponding quarter of the previous financial year, representing an increase of approximately 19%.
However, iron ore sales stood at 104.83 lakh tonnes, compared with 107.16 lakh tonnes in Q2 FY26, registering a decline of around 2%.
The company reported revenue from operations of ₹6,638 crore during the quarter, compared with ₹6,261 crore in Q2 FY26, reflecting growth of approximately 6%.
The average domestic iron ore realisation improved to ₹5,488 per tonne from ₹4,973 per tonne in the corresponding quarter last year, an increase of approximately 10%.
These figures indicate that higher iron ore realisations and increased production supported revenue growth despite slightly lower quarterly sales volumes.
Financial Performance: H1 FY27
NMDC’s financial performance during the first half of FY27 reflected moderate growth in revenue and profitability.
The company reported revenue from operations of ₹13,433 crore, compared with ₹12,895 crore in H1 FY26.
Total income increased to ₹14,274 crore from ₹13,574 crore, registering growth of approximately 5%.
Other key financial indicators include:
- EBITDA: ₹5,253 crore, compared with ₹5,162 crore.
- EBITDA margin: 39%, compared with 40%.
- Profit before tax (PBT): ₹4,953 crore, compared with ₹4,914 crore.
- Profit after tax (PAT): ₹3,674 crore, compared with ₹3,663 crore.
Profit after tax increased marginally by approximately 0.3%, indicating that higher revenue did not translate into a comparable increase in net earnings.
The company’s financial performance was influenced by an increase in operating expenses, royalty and other statutory levies.
Q2 FY27 Financial Results
For the quarter ended September 30, 2026, NMDC reported revenue from operations of ₹6,638 crore, compared with ₹6,261 crore in Q2 FY26.
Its EBITDA increased to ₹2,436 crore from ₹2,385 crore, while the EBITDA margin stood at 37%, compared with 38% in the corresponding quarter last year.
Profit after tax was ₹1,667 crore, compared with ₹1,694 crore in Q2 FY26, reflecting a marginal year-on-year decline of approximately 2%.
The results demonstrate that the company maintained revenue and operating earnings growth despite cost pressures during the quarter.
Rising Costs Remain an Important Area to Monitor
Although NMDC recorded substantial production growth, higher expenses affected the pace of profitability improvement.
During H1 FY27, total expenses increased by approximately 8% to ₹9,321 crore from ₹8,660 crore in the corresponding period last year.
Royalty and other levies increased by approximately 31% to ₹2,976 crore, while additional amounts linked to royalty increased by around 30% to ₹3,349 crore.
Operational expenses also increased during the period.
These cost developments contributed to the relatively modest growth in EBITDA and profit after tax compared with the increase in production.
Going forward, controlling operating costs, improving logistics, increasing sales volumes and maintaining favourable iron ore realisations will remain important for sustaining profitability.
NMDC’s Role in India’s Steel Industry
NMDC plays a strategic role in India’s mining and steel value chain by supplying iron ore, a critical raw material used in steel manufacturing.
The company operates major iron ore mines in Chhattisgarh and Karnataka and continues to invest in mining infrastructure, mechanisation, logistics and capacity expansion.
Its production performance is closely linked to the requirements of India’s expanding steel industry.
As the country continues to develop infrastructure, housing, railways, roads, industrial facilities and manufacturing capabilities, the demand for steel and its essential raw materials remains an important economic driver.
NMDC’s efforts to increase production capacity and strengthen supply infrastructure are therefore significant for India’s long-term mineral security and industrial development.
Outlook for FY2026-27
The first-half performance provides an indication of NMDC’s operational momentum for the remainder of FY27.
The 23% increase in iron ore production demonstrates the company’s ability to expand output. However, converting higher production into increased sales and improved profitability will be important priorities.
Key factors to watch during the second half include:
- Sustaining higher iron ore production.
- Improving sales volumes and inventory management.
- Maintaining competitive iron ore realisations.
- Controlling mining and statutory costs.
- Strengthening transportation and logistics infrastructure.
- Expanding value-added activities, including pellet production.
The company’s performance in these areas will influence its full-year financial results and contribution to India’s domestic steel industry.
Conclusion
NMDC Limited’s Q2 and H1 FY27 performance highlights its continued operational expansion and strategic importance to India’s mining and steel sectors.
With first-half iron ore production rising 23% to 272.72 lakh tonnes and revenue from operations reaching a record ₹13,433 crore, the company has maintained positive business momentum.
At the same time, relatively flat sales volumes and rising operating expenses underline the importance of improving cost efficiency and converting higher production into stronger revenue and profitability.
As India advances its infrastructure development and domestic steel manufacturing ambitions, NMDC is expected to remain an important contributor to the country’s mineral and industrial ecosystem.
The Worldonomics Times will continue to track NMDC’s production performance, financial results, mining expansion projects and other developments across India’s public-sector enterprises.