Access to affordable and timely finance remains one of the biggest challenges for Micro, Small and Medium Enterprises (MSMEs), particularly micro and small businesses. Many entrepreneurs have viable business ideas but lack adequate collateral, formal credit history or access to institutional finance.
The Pradhan Mantri MUDRA Yojana (PMMY) was launched by the Government of India on 8 April 2015 with the objective of providing institutional, collateral-free credit to micro enterprises. Over the years, the scheme has become an important part of India’s financial inclusion and entrepreneurship ecosystem.
The scheme follows the broader vision of “Funding the Unfunded”, helping small entrepreneurs access formal credit for income-generating business activities.
What is the MUDRA Scheme?
MUDRA stands for Micro Units Development and Refinance Agency. Under PMMY, eligible borrowers can obtain loans through participating lending institutions for starting, expanding or strengthening small businesses.
MUDRA loans can support both term-loan and working-capital requirements. Eligible activities cover manufacturing, trading and services, as well as certain activities allied to agriculture, including poultry, dairy and beekeeping.
The scheme is particularly relevant to micro enterprises that may find it difficult to access conventional business finance because of limited collateral or credit history.
Four Categories of MUDRA Loans
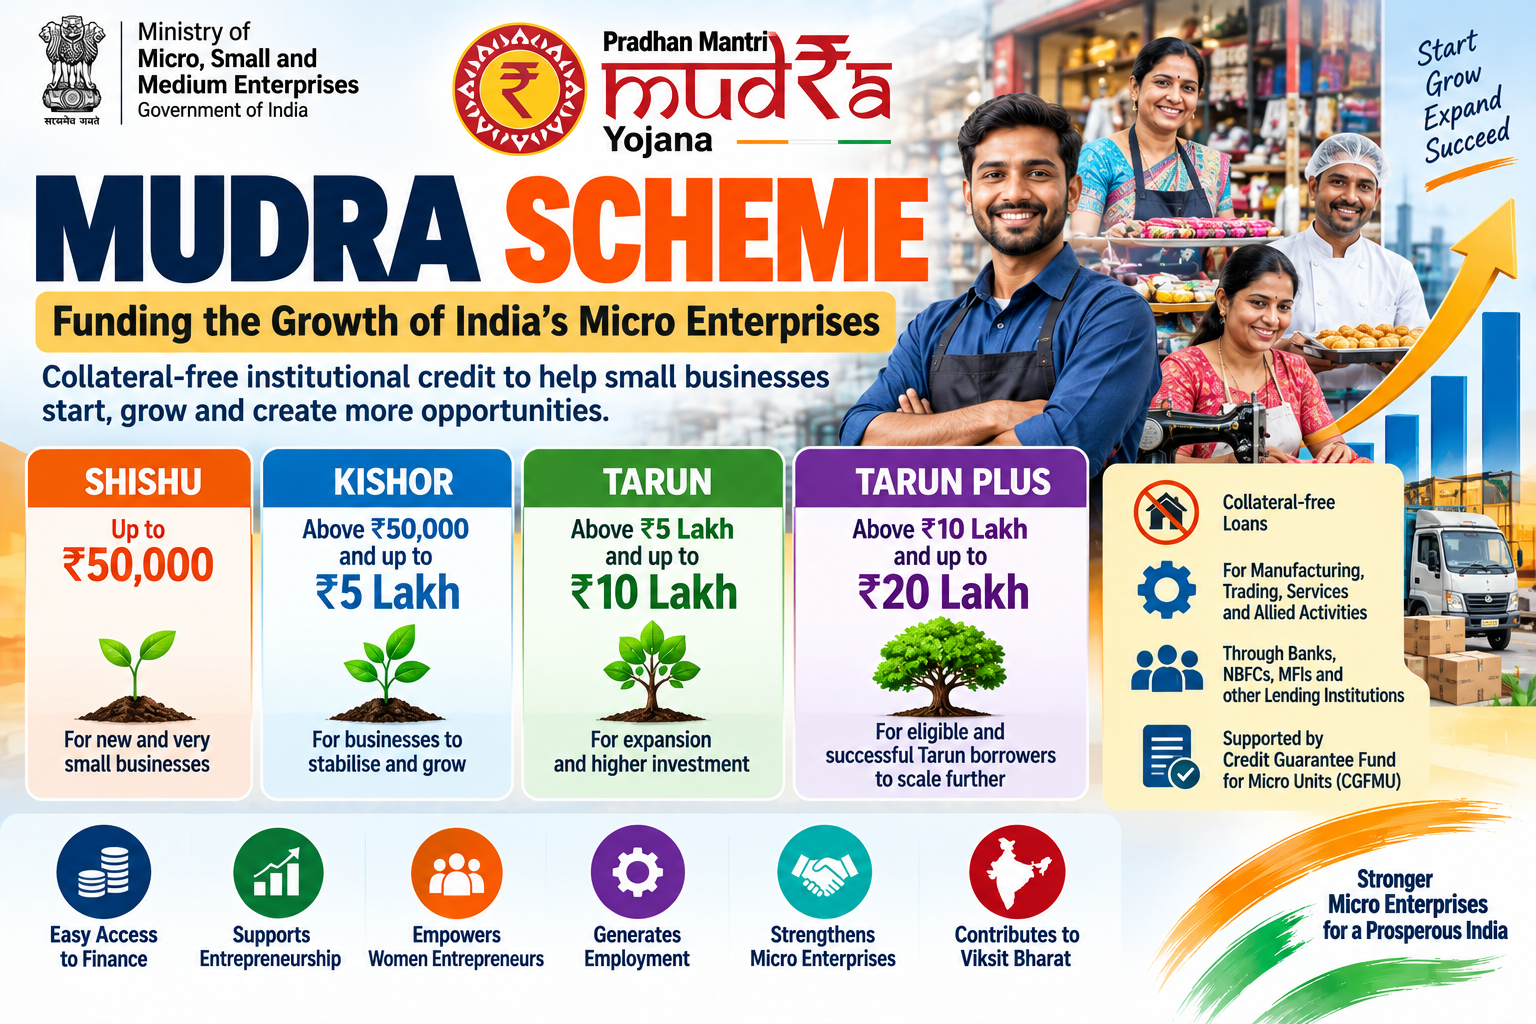
PMMY now has four categories based broadly on the stage of development and financing requirement of the enterprise.
1. Shishu
Loan amount: Up to ₹50,000
Shishu is designed primarily for very small or early-stage businesses. It can be useful for entrepreneurs who are starting a small activity or need limited capital to establish or strengthen their operations.
Examples can include small retail businesses, repair services and other micro-enterprise activities.
2. Kishor
Loan amount: Above ₹50,000 and up to ₹5 lakh
Kishor is intended for businesses that require more capital to stabilise operations, purchase equipment, manage working capital or expand an existing activity.
For a growing micro enterprise, this category can provide an important step between very small initial financing and larger business expansion.
3. Tarun
Loan amount: Above ₹5 lakh and up to ₹10 lakh
Tarun is aimed at enterprises requiring a larger level of financing for expansion, capacity enhancement, equipment investment or other business requirements.
An entrepreneur who has established a viable business model may use this level of financing to increase production, expand market reach or strengthen infrastructure.
4. Tarun Plus
Loan amount: Above ₹10 lakh and up to ₹20 lakh
Tarun Plus is the newest category under PMMY. It was introduced following the enhancement of the maximum MUDRA loan limit from ₹10 lakh to ₹20 lakh.
Tarun Plus is intended for entrepreneurs who have successfully repaid a previous Tarun-category loan. The category provides an opportunity for successful borrowers to access a higher level of collateral-free institutional finance as their businesses grow. The eligibility condition applies to qualifying Tarun borrowers from 24 October 2024 onward.
This creates a progression pathway: an entrepreneur can start small, establish a repayment track record and potentially move towards higher levels of financing.
What Can MUDRA Loans Be Used For?
MUDRA financing can support a wide range of income-generating activities.
These may include:
- Manufacturing businesses
- Retail and trading activities
- Service enterprises
- Repair and maintenance businesses
- Transport-related activities
- Food-related businesses
- Small workshops
- Poultry
- Dairy
- Beekeeping
- Other eligible allied agricultural activities
The exact eligibility and financing conditions are determined under the applicable PMMY framework and by the lending institution.
Collateral-Free Institutional Credit
One of the most important features of PMMY is that collateral is not required under the scheme framework.
This is particularly significant for micro entrepreneurs who may have a viable business but do not own sufficient property or other assets to offer as security.
The Government has also established guarantee support through the Credit Guarantee Fund for Micro Units (CGFMU) for eligible MUDRA loans. Following the 2024 enhancement, guarantee coverage was extended to qualifying PMMY loans up to ₹20 lakh.
However, collateral-free does not mean automatic approval. Banks and other lending institutions still assess the applicant’s business proposal, repayment capacity, financial information and applicable lending criteria.
Who Provides MUDRA Loans?
MUDRA loans are provided through Member Lending Institutions (MLIs).
These include:
- Public Sector Banks
- Private Sector Banks
- Regional Rural Banks
- Small Finance Banks
- Foreign Banks
- NBFCs
- Micro Finance Institutions
- NBFC-MFIs
This broad lending network allows entrepreneurs in different parts of the country to access formal credit channels.
MUDRA and Women Entrepreneurs
Women entrepreneurs have been significant beneficiaries of the MUDRA ecosystem. Government data released in 2026 highlighted the scheme’s contribution to women-led entrepreneurship and financial inclusion.
The scheme is particularly relevant for small businesses where women entrepreneurs may otherwise face barriers related to collateral, formal credit history or access to institutional finance.
MUDRA’s Contribution to Financial Inclusion
The scale of PMMY demonstrates its importance in India’s entrepreneurial ecosystem.
According to the Government, as of 27 March 2026, PMMY had sanctioned more than 57.79 crore loans, with total sanctioned amount exceeding ₹40.07 lakh crore since its launch.
These numbers demonstrate how formal institutional credit has increasingly reached micro businesses and individual entrepreneurs across India.
How Entrepreneurs Can Apply
An entrepreneur should first identify the purpose and amount of finance required and prepare a realistic business plan or project proposal.
The applicant can approach an eligible lending institution and submit the required documents. Depending on the lender and application channel, the process may also be facilitated through digital platforms such as Jan Samarth.
Applicants should maintain proper financial records and clearly demonstrate how the proposed loan will generate income and support repayment.
MUDRA as a Growth Ladder for MSMEs
One of the most important aspects of PMMY is that its four categories can reflect different stages of business development.
An entrepreneur may begin with a small Shishu loan, move to Kishor as the business stabilises, access Tarun for larger expansion and, subject to the specific eligibility condition, potentially progress to Tarun Plus after successfully repaying a previous Tarun loan.
This creates a financing pathway that can accompany an entrepreneur’s journey from starting a business to scaling it.
Conclusion
The Pradhan Mantri MUDRA Yojana has emerged as a significant instrument for expanding access to institutional finance for India’s micro entrepreneurs.
With collateral-free loans up to ₹20 lakh, four categories—Shishu, Kishor, Tarun and Tarun Plus—and coverage across manufacturing, trading, services and eligible allied agricultural activities, PMMY provides financing opportunities at different stages of business development.
For entrepreneurs, however, access to credit should be accompanied by proper financial planning, disciplined working-capital management and timely repayment.
Ultimately, MUDRA’s greatest potential lies not simply in providing loans, but in helping small businesses enter the formal financial system, build credit histories, invest in growth and create sustainable livelihoods.
From a small business idea to a growing enterprise, MUDRA aims to make finance more accessible at every stage of the entrepreneurial journey.