New Delhi | October 26, 2026
Bharat Coking Coal Limited (BCCL), a subsidiary of Coal India Limited, has reported a significant turnaround in its financial performance for the second quarter of FY2026-27, returning to profitability after reporting a loss in the corresponding period last year.
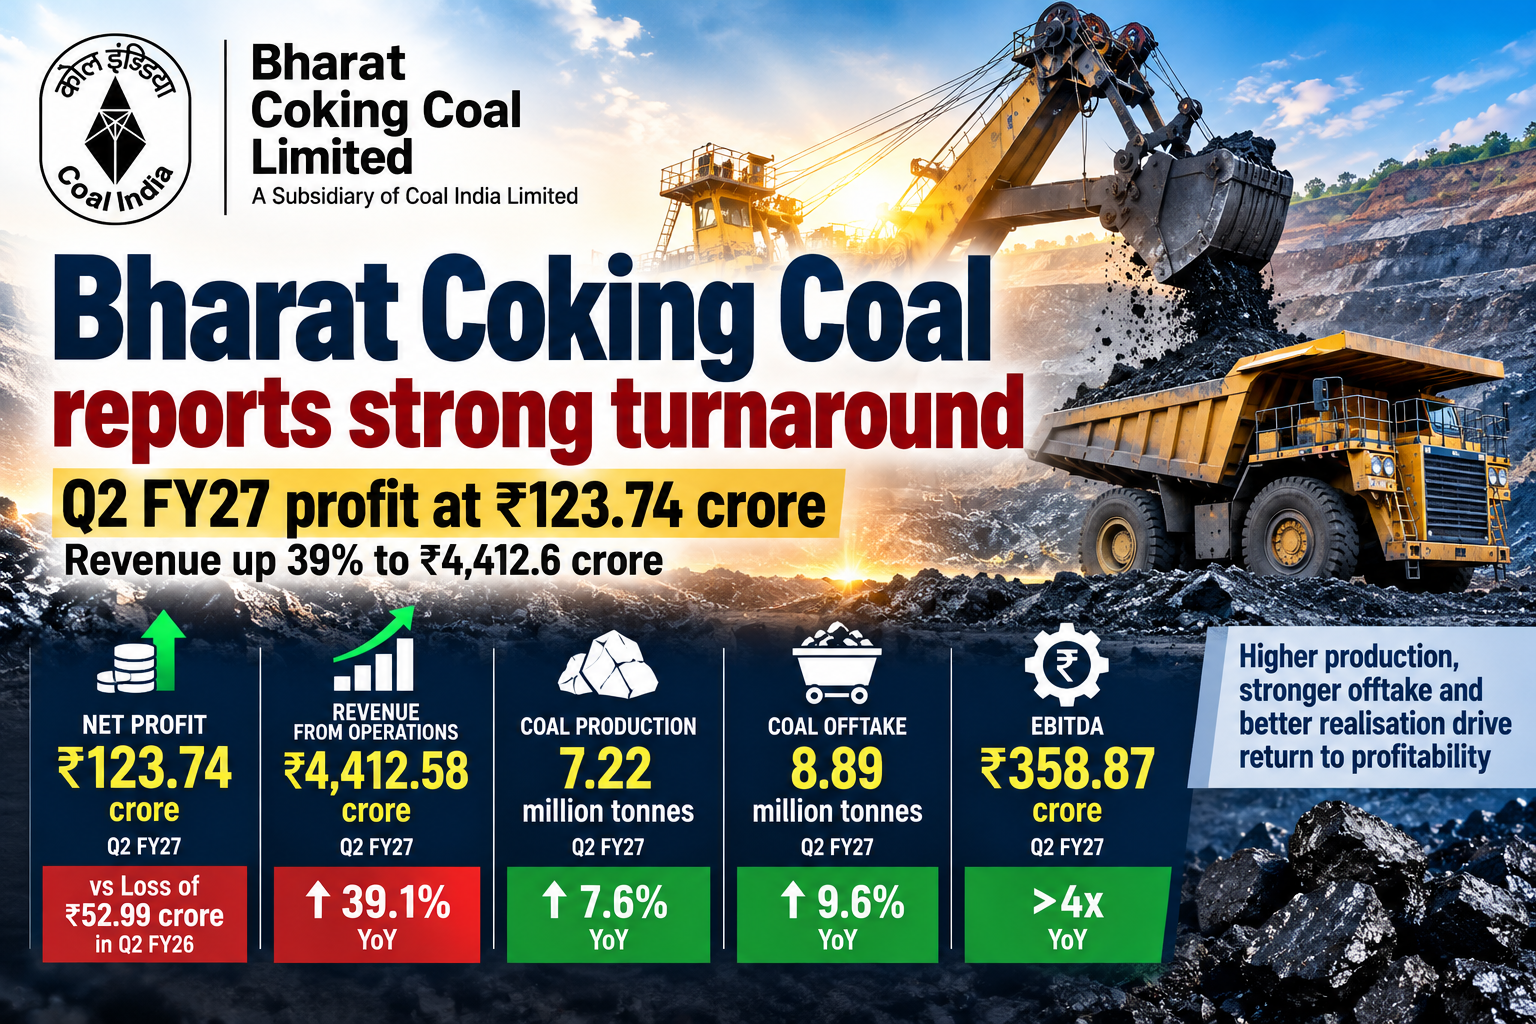
The company posted a net profit of ₹123.74 crore for Q2 FY27, compared with a net loss of ₹52.99 crore in Q2 FY26. The turnaround comes alongside a sharp improvement in revenue, stronger coal production and higher offtake during the September quarter.
Revenue jumps 39%
BCCL’s revenue from operations increased 39.1% year-on-year to ₹4,412.58 crore in Q2 FY27, compared with ₹3,173.25 crore in the corresponding quarter of FY26.
Total income, including other income, stood at ₹4,571.15 crore, compared with ₹3,643.54 crore a year earlier, representing growth of approximately 25.5%.
The company also moved from a quarterly loss to a profit before tax of ₹185.78 crore, compared with a loss before tax of ₹48.06 crore in Q2 FY26.
The latest performance marks a substantial improvement over the first quarter of FY27, when BCCL had reported a net loss of ₹68.09 crore.
Production and offtake improve
Operational performance also strengthened during the quarter.
BCCL’s raw coal production increased 7.6% to 7.22 million tonnes (MT) in Q2 FY27 from 6.71 MT in the year-ago quarter.
Raw coal offtake increased even faster, rising 9.6% to 8.89 MT, compared with 8.11 MT in Q2 FY26. The improvement in production and dispatches provided additional support to the company’s quarterly performance.
However, the half-year picture remains mixed. Production for H1 FY27 stood at around 13.78 MT, lower than 15.75 MT in H1 FY26, while first-half offtake was 16.61 MT against 17.05 MT a year earlier. This makes the second-quarter improvement particularly important for the company’s efforts to strengthen its full-year performance.
Strong improvement in washery performance
One of the notable contributors to the turnaround was the company’s washery business.
BCCL’s washeries reported a profit of ₹235.51 crore in Q2 FY27, compared with a loss of ₹2.12 crore in the corresponding quarter of the previous year.
Coal feed to the washeries also increased to 15.51 lakh tonnes, compared with 12.15 lakh tonnes a year earlier.
The improvement highlights the growing importance of coal beneficiation and value-added processing in enhancing realisations and operational efficiency.
Better realisation and collections
The company also benefited from improved sales realisation.
BCCL’s average washed coking coal price reportedly increased to around ₹12,681 per tonne from ₹9,437 per tonne, while its overall sales realisation strengthened significantly.
The company reported an all-time high H1 sales realisation of approximately ₹10,259.63 crore, compared with ₹7,817.65 crore in the previous year. September also saw a record monthly collection of ₹2,378.94 crore.
Improved collections have also helped strengthen the company’s working-capital position. Gross trade receivables declined during the first half of the year, indicating better cash-flow management.
EBITDA rises sharply
BCCL’s operating performance was reflected in a substantial improvement in EBITDA.
Quarterly EBITDA increased more than fourfold to approximately ₹358.87 crore, compared with ₹86.65 crore in Q2 FY26.
The improvement suggests that the company’s return to profitability was supported not merely by higher revenue but also by stronger operating performance.
Nevertheless, maintaining margins will remain important as the company navigates fluctuations in coal prices, production costs and demand from the steel sector.
Investment in infrastructure and capacity
BCCL is also pursuing operational modernisation and capacity enhancement.
During the quarter, the company commissioned the 2 MTPA Bhojudih washery, taking its overall washing capacity to approximately 17.35 MT.
It also operationalised its first 5 MTPA First Mile Connectivity project at Maheshpur, aimed at improving coal evacuation and logistics efficiency.
BCCL has further commenced MDO production at the Katras ASGKCC mine and signed an MoU with Steel Authority of India Limited (SAIL) for development of the 4 MTPA Kalyaneshwari Block.
These initiatives could strengthen BCCL’s production, processing and evacuation capabilities over the medium term.
Capex remains a key focus
The company spent approximately ₹630.77 crore on capital expenditure during H1 FY27, against a full-year FY27 target of ₹1,000 crore.
Continued investment will be important as BCCL seeks to modernise mining operations, improve coal evacuation, expand washing capacity and enhance productivity.
For a company operating in one of India’s most important coking-coal regions, such investments also have broader strategic significance for the domestic steel industry.
Strategic importance for India’s steel sector
BCCL is a major producer of coking coal and plays an important role in India’s efforts to strengthen domestic availability of a critical raw material for steel production.
India remains heavily dependent on imports to meet a substantial portion of its coking-coal requirement. Consequently, increasing domestic production and improving the quality and processing of indigenous coking coal remain important policy and industrial priorities.
BCCL’s operational improvements, therefore, have significance beyond its own financial statements.
Higher production, better washing infrastructure and improved evacuation systems can contribute to a more reliable domestic supply chain for the steel industry.
Outlook
BCCL’s Q2 FY27 results demonstrate a meaningful recovery from the weak performance recorded in the first quarter and the year-ago period.
The combination of 39% revenue growth, a return to profitability, higher coal production, stronger offtake, improved washery performance and increased operating earnings represents a positive quarter for the Coal India subsidiary.
At the same time, the company will need to sustain production and dispatch growth through the second half of FY27. The decline in first-half production compared with the previous year indicates that the recovery will need to be maintained over multiple quarters before it can be considered fully established.
With continued investment in washeries, mine development, first-mile connectivity and other infrastructure, BCCL is positioning itself to improve productivity and strengthen its contribution to India’s domestic coking-coal ecosystem.
Key Numbers — Q2 FY27
| Indicator | Q2 FY27 | Q2 FY26 | Change |
|---|---|---|---|
| Revenue from operations | ₹4,412.58 crore | ₹3,173.25 crore | +39.1% |
| Net profit | ₹123.74 crore | Loss ₹52.99 crore | Turnaround |
| Total income | ₹4,571.15 crore | ₹3,643.54 crore | +25.5% |
| Coal production | 7.22 MT | 6.71 MT | +7.6% |
| Coal offtake | 8.89 MT | 8.11 MT | +9.6% |
| EPS | ₹0.27 | -₹0.11 | Improved |
The Worldonomics Times Take
BCCL’s Q2 performance signals a strong operational recovery, but sustaining production growth and profitability during the second half of FY27 will be crucial. With coking coal strategically important for India’s steel ambitions, the company’s investments in mining, washing and evacuation infrastructure could have significance well beyond its balance sheet.