Introduction: When Profit Does Not Mean Financial Strength
Imagine a small manufacturing business that receives a large order, manufactures the products, delivers them to the customer and records a healthy profit in its books. On paper, the business appears successful. However, when the time comes to pay employees, suppliers, electricity bills and loan instalments, the business struggles to arrange sufficient funds.
What went wrong?
The answer may not be a lack of profitability. It may be a lack of cash.
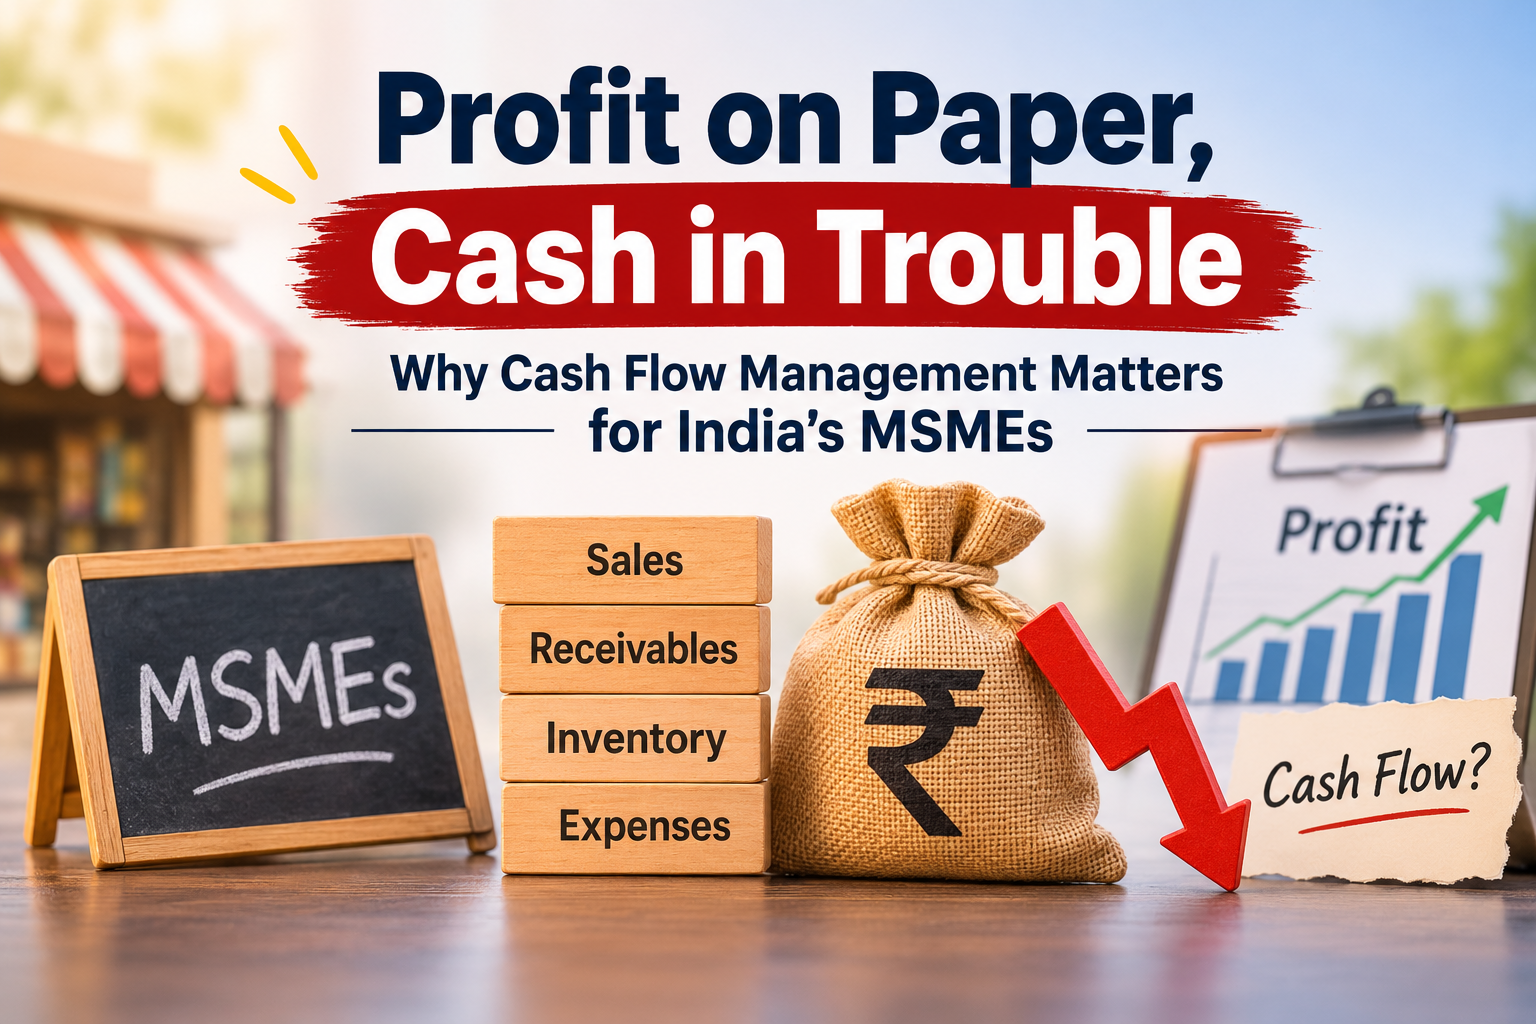
This situation reflects one of the most important financial challenges faced by Micro, Small and Medium Enterprises (MSMEs) in India: the gap between accounting profit and actual cash availability.
Profitability indicates whether a business earns more than it spends over a period, whereas cash flow reflects whether it has sufficient money available to meet its immediate financial obligations. Both are important, but neither can substitute for the other.
For MSMEs, where financial resources and access to external funding may be limited, effective cash flow management is not merely an accounting exercise; it is essential for survival and sustainable growth.
1. Understanding the Profit–Cash Flow Gap
One of the most common financial misconceptions is that a profitable business must also have a healthy cash position.
Consider a simple example.
An MSME manufactures goods worth ₹10 lakh and sells them to a customer on 60 days’ credit. The business records the sale and recognises the applicable profit. However, it must pay ₹6 lakh towards raw materials, ₹2 lakh towards salaries and ₹1 lakh towards other operating expenses before receiving the customer’s payment.
Although the transaction generates an accounting profit of ₹1 lakh, the business may face an immediate cash shortage of ₹9 lakh.
This happens because revenue recognition and cash collection do not necessarily occur at the same time.
In accounting terms, profit is generally measured using the accrual basis, while cash flow tracks actual inflows and outflows of money.
Therefore, a business can report profits and still face liquidity problems.
2. Why Cash Flow Management Is a Major Challenge for Indian MSMEs
India’s MSME sector plays an important role in employment generation, manufacturing, exports and economic development. However, several operational and financial challenges affect its ability to maintain healthy cash flows.
A. Delayed payments from customers
Delayed payments are among the biggest challenges faced by micro and small enterprises. When customers postpone payments, the funds required for daily operations remain locked in trade receivables.
The Economic Survey 2025–26 highlighted that an estimated ₹8.1 lakh crore was locked in delayed payments to MSMEs. This indicates the scale of the liquidity challenge affecting smaller businesses.
B. Increasing working capital requirements
MSMEs need continuous funds to maintain inventory, purchase raw materials, pay employees and meet other operating expenses.
When a significant amount of money remains blocked in receivables or unsold inventory, businesses may struggle to finance their regular operations.
C. Dependence on external borrowing
To overcome temporary cash shortages, businesses may depend on working capital loans, overdrafts or other credit facilities.
While borrowing can support business operations, excessive dependence on expensive short-term finance increases interest costs and reduces profitability.
D. Poor financial forecasting
Many small businesses concentrate on sales, production and customer acquisition but give insufficient attention to cash flow forecasting.
Without estimating future cash receipts and payments, even a growing enterprise may find itself unprepared for financial obligations.
3. Cash Flow Management: More Than Tracking Bank Balances
Effective cash flow management means planning, monitoring and controlling the movement of money into and out of a business.
It requires management to understand not only how much money is available today but also how much will be required tomorrow.
Some practical measures include:
1. Prepare a regular cash flow forecast
Businesses should prepare weekly or monthly cash flow projections covering expected receipts, supplier payments, salaries, taxes, loan repayments and other expenses.
This helps management identify potential shortages before they become serious problems.
2. Strengthen receivables management
Businesses should establish clear credit policies, communicate payment terms to customers, monitor outstanding invoices and follow up on overdue payments.
Faster collections can release funds already earned by the business without necessarily requiring additional borrowing.
3. Optimise inventory levels
Excess inventory blocks working capital and increases storage and holding costs. Businesses should maintain appropriate stock levels based on demand, production requirements and supplier lead times.
4. Manage payables strategically
Businesses should negotiate reasonable payment terms with suppliers and plan payments according to agreed contractual obligations.
The objective should be to maintain liquidity without damaging supplier relationships or delaying legitimate payments.
5. Maintain an emergency liquidity reserve
A reasonable cash buffer can help businesses manage unexpected expenses, temporary reductions in sales or delays in customer payments.
4. Government Initiatives: Supporting MSME Liquidity
Recognising the importance of timely payments, the Government of India has introduced various mechanisms to address delayed payment issues.
MSMED Act, 2006 – Section 15
The provision requires buyers to make payments to micro and small enterprises within the agreed period, which cannot exceed 45 days from the date of acceptance or deemed acceptance. Where there is no written agreement, the statutory time limit is 15 days.
MSME Samadhaan and Online Dispute Resolution
The MSME Samadhaan mechanism enables eligible micro and small enterprises to raise delayed payment disputes before the relevant Micro and Small Enterprises Facilitation Council. The Online Dispute Resolution mechanism provides a structured digital approach to resolving such disputes.
Trade Receivables Discounting System (TReDS)
TReDS is an electronic platform that facilitates the financing of trade receivables of MSMEs through financiers. It can help eligible businesses obtain funds against accepted invoices instead of waiting until the buyer’s payment date.
These initiatives aim to improve payment discipline and provide better access to working capital. However, awareness, timely implementation and effective utilisation remain important.
5. The Role of Financial Discipline in Sustainable Growth
A successful business should not measure its performance only through turnover and net profit. It should also evaluate how efficiently it converts sales into cash.
Some important indicators include:
- Operating Cash Flow: Cash generated from regular business operations.
- Debtor Collection Period: The average time taken to collect payments from customers.
- Inventory Turnover: How efficiently inventory is converted into sales.
- Current Ratio: The relationship between current assets and current liabilities.
- Cash Conversion Cycle: The time taken to convert investment in inventory and other operating resources into cash collected from customers.
Monitoring these indicators can help business owners identify financial weaknesses and take corrective action.
For MSMEs, financial discipline should become a regular management practice rather than an activity performed only at the time of preparing financial statements.
Conclusion: Profit Creates Growth, Cash Sustains Business
The long-term success of an enterprise depends not only on its ability to generate profits but also on its ability to manage liquidity.
A business may have strong sales, an impressive order book and positive accounting results, but without sufficient cash, its day-to-day operations can come under pressure.
For India’s MSMEs, the next step towards sustainable growth must include stronger financial planning, disciplined working capital management, timely receivables collection and greater awareness of available financing mechanisms.
Ultimately, the strength of a business should not be judged merely by the profit it reports, but also by its ability to convert that profit into cash and meet its financial commitments.
Because profit may indicate success on paper, but cash flow keeps the business alive.