Published: 14 November 2026
Important for companies undertaking international and specified domestic transactions
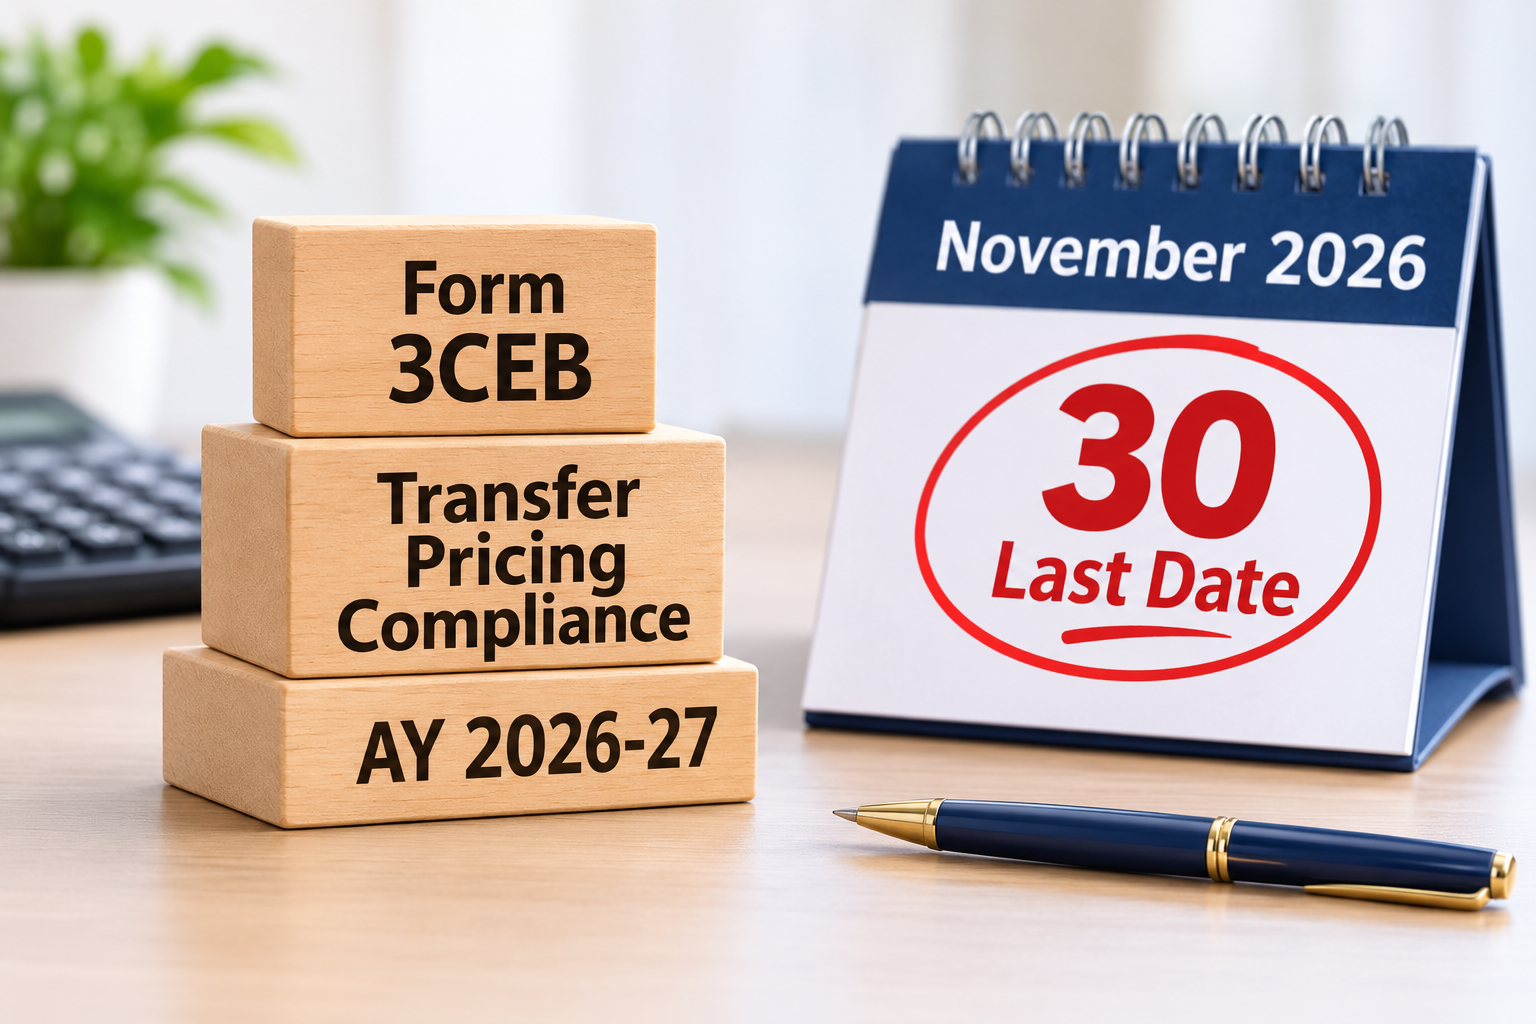
Transfer pricing compliance is an important area of corporate taxation, particularly for businesses having transactions with associated enterprises. With the income-tax return filing deadline for taxpayers covered by transfer pricing provisions approaching on 30 November 2026, companies and tax professionals should ensure that all statutory reporting and documentation requirements are completed within the prescribed timelines.
The transfer pricing framework aims to ensure that transactions between associated enterprises are undertaken at arm’s length prices and that profits are not artificially shifted to jurisdictions offering lower tax rates.
1. Who is required to comply with transfer pricing provisions?
The transfer pricing provisions under the Income-tax Act, 1961, primarily apply to taxpayers entering into:
- International transactions with associated enterprises.
- Specified domestic transactions exceeding the prescribed threshold of ₹20 crore during the previous year.
- Other transactions covered under the applicable transfer pricing provisions.
International transactions may include purchases and sales of goods, provision of services, payment of royalties, interest on loans, guarantees, and other financial or commercial arrangements between associated enterprises.
Specified domestic transactions are certain prescribed transactions between related parties that fall within the scope of transfer pricing provisions.
2. Form 3CEB: Mandatory reporting requirement
One of the most important compliance requirements is the filing of Form 3CEB, which is an accountant’s report under Section 92E of the Income-tax Act, 1961.
Every person entering into an international transaction or specified domestic transaction during the relevant previous year is required to obtain and furnish a report from an accountant in the prescribed format.
Form 3CEB contains important particulars, including:
- Details of associated enterprises.
- Nature and value of international transactions.
- Details of specified domestic transactions, wherever applicable.
- Transfer pricing methods adopted for determining the arm’s length price.
- Details of adjustments, if any, made to the transaction values.
The report helps the Income-tax Department examine whether transactions between related parties comply with the arm’s length principle.
3. Income-tax Return Filing Deadline: 30 November 2026
Taxpayers subject to transfer pricing provisions are required to file their income-tax returns by 30 November 2026 for Assessment Year 2026-27, subject to the applicable statutory provisions and any subsequent extension.
Form 3CEB must also be furnished within the prescribed time. Accordingly, businesses should ensure that the accountant’s report is completed and filed before the applicable return filing deadline.
Delay in furnishing the report or filing the return may result in additional compliance requirements and possible penal consequences.
4. Transfer Pricing Documentation: What should companies maintain?
Apart from filing Form 3CEB, taxpayers must maintain appropriate documentation supporting the arm’s length nature of their transactions.
Under Section 92D read with Rule 10D of the Income-tax Rules, 1962, prescribed transfer pricing documentation generally includes:
- Ownership structure and details of associated enterprises.
- Description of the business activities and industry.
- Nature and terms of international transactions.
- Functions performed, assets employed and risks assumed (FAR analysis).
- Selection and justification of the most appropriate transfer pricing method.
- Comparable uncontrolled transactions and benchmarking analysis.
- Computation of the arm’s length price.
Proper documentation is essential to substantiate the pricing methodology adopted by the taxpayer and to respond effectively to queries raised by tax authorities.
5. Consequences of Non-Compliance
Failure to comply with transfer pricing reporting and documentation requirements may attract significant penalties under the Income-tax Act, 1961.
| Non-compliance | Relevant provision | Penalty |
|---|---|---|
| Failure to furnish Form 3CEB | Section 271BA | ₹1 lakh |
| Failure to maintain prescribed documentation | Section 271AA | 2% of transaction value |
| Failure to report an international transaction | Section 271AA | 2% of transaction value |
| Under-reporting or misreporting of income due to transfer pricing adjustments | Section 270A | As applicable |
The applicability of penalties depends on the facts, circumstances and statutory conditions of each case.
6. Professional Implications and Practical Recommendations
With the 30 November 2026 deadline approaching, companies should undertake an immediate review of their transfer pricing compliance.
Tax professionals should particularly focus on reconciling international transactions with the books of accounts, Form 26AS, financial statements and related-party disclosures. They should also verify whether all transactions with associated enterprises have been appropriately identified and reported.
Companies should complete benchmarking studies, review inter-company agreements and ensure consistency between Form 3CEB, transfer pricing documentation and the income-tax return.
Conclusion
Transfer pricing compliance is not merely a reporting formality; it is an essential mechanism for ensuring transparency and preventing profit shifting between associated enterprises.
The 30 November 2026 deadline for AY 2026-27 makes it important for companies and tax professionals to complete Form 3CEB, maintain adequate supporting documentation and file their income-tax returns within the prescribed timeline.
A timely and comprehensive compliance review can help businesses minimise litigation risks, avoid penalties and maintain transparency in their related-party transactions.