Introduction
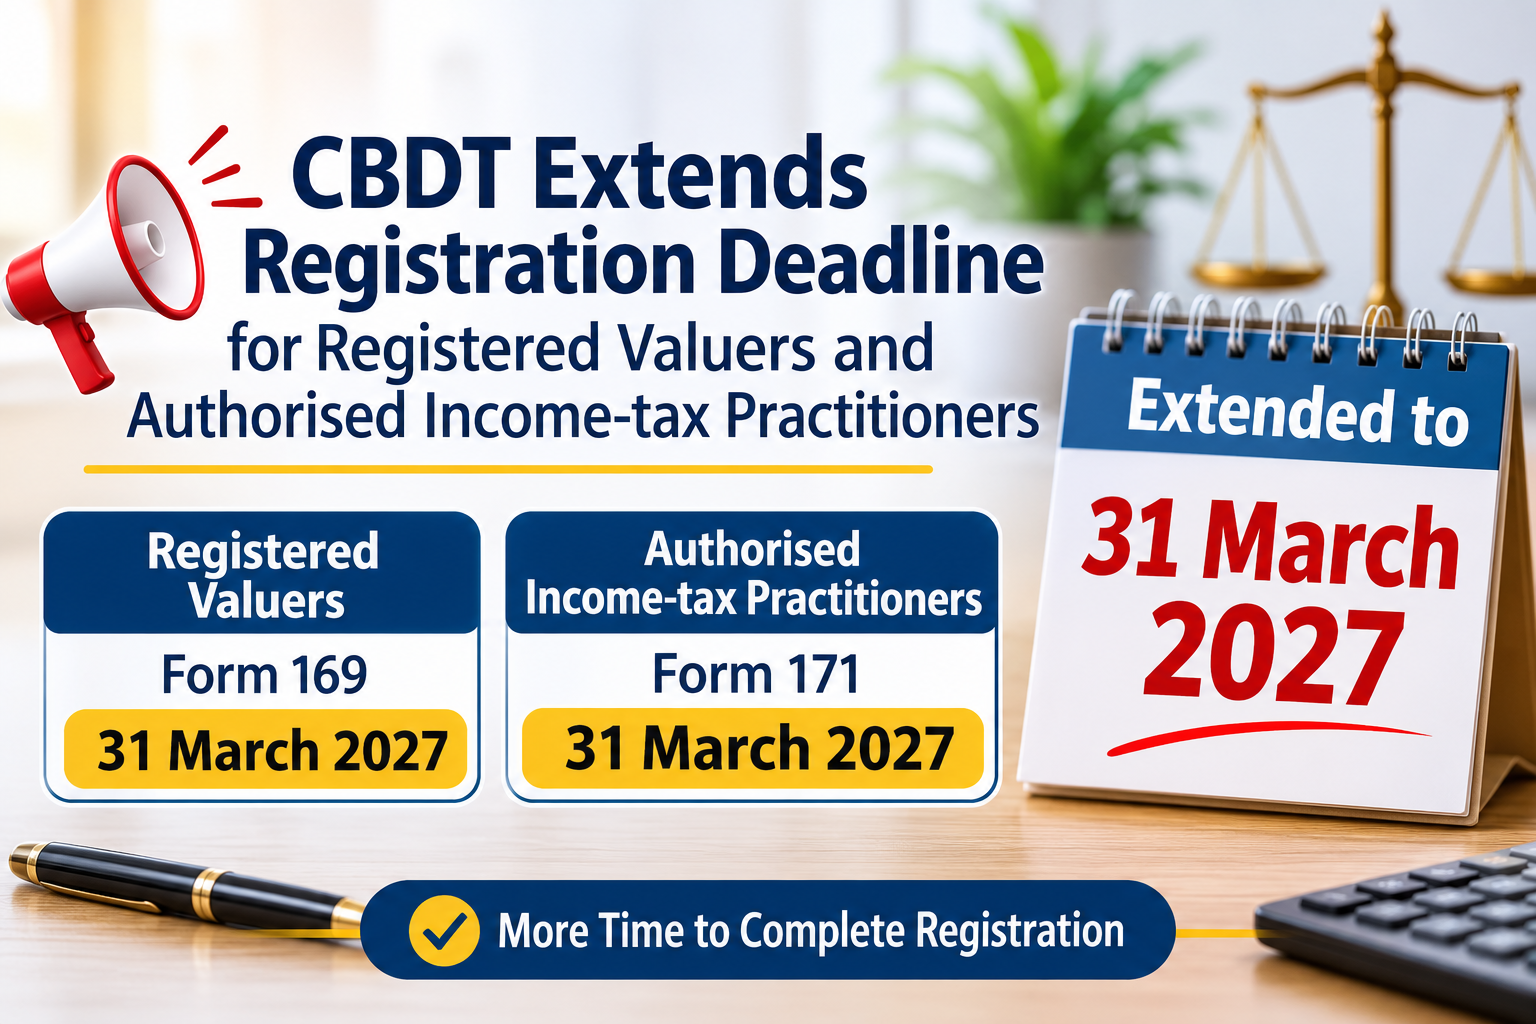
The Central Board of Direct Taxes (CBDT) has provided significant relief to professionals by extending the deadline for registration of Registered Valuers and Authorised Income-tax Practitioners under the Income-tax Act, 2025.
The extension has been notified through the Income-tax (Fourth Amendment) Rules, 2026, vide Notification No. 120/2026 dated 17 September 2026.
Under this amendment, the earlier registration deadline of 30 September 2026 has been extended to 31 March 2027, allowing additional time for eligible professionals to complete the prescribed registration formalities.
1. Background of the Amendment
With the introduction of the Income-tax Act, 2025 and the Income-tax Rules, 2026, a revised regulatory framework has been established for various tax-related professionals.
The new framework prescribes registration requirements for Registered Valuers and Authorised Income-tax Practitioners under Sections 514 and 515 of the Income-tax Act, 2025, respectively.
Considering the transition to the new regulatory framework, CBDT has extended the prescribed timelines to provide professionals with additional time to comply with the registration requirements.
2. Extension of Registration Deadline
The amendment substitutes the earlier date of 30 September 2026 with 31 March 2027 under Rule 246(4) and Rule 256(4) of the Income-tax Rules, 2026.
The revised deadlines are as follows:
| Category of professional | Relevant form | Revised deadline |
|---|---|---|
| Registered Valuers | Form No. 169 | 31 March 2027 |
| Authorised Income-tax Practitioners | Form No. 171 | 31 March 2027 |
Accordingly, eligible professionals falling within the prescribed categories can utilise the extended timeline to complete their registration formalities.
3. Revised Forms 169 and 171
Apart from extending the registration deadline, CBDT has also substituted the prescribed application forms to streamline the registration process.
A. Form No. 169 – Registration as a Registered Valuer
Form No. 169 is prescribed for professionals seeking registration as valuers under Section 514 of the Income-tax Act, 2025.
The revised form requires relevant particulars, including:
- Personal and professional details of the applicant.
- Educational qualifications and relevant experience.
- Details of valuation work undertaken.
- Information regarding previous registration under the Wealth-tax Act, 1957, wherever applicable.
B. Form No. 171 – Registration as an Authorised Income-tax Practitioner
Form No. 171 is prescribed for applications seeking registration as an Authorised Income-tax Practitioner under Section 515 of the Income-tax Act, 2025.
The revised form provides the prescribed mechanism for furnishing the applicant’s particulars and declaration for registration.
4. Other Important Changes Introduced
The notification also introduces certain additional amendments to the Income-tax Rules, 2026.
One notable change relates to Rule 176(3)(a)(ii), whereby the requirement of communication by affixing a digital signature has been replaced with communication by way of electronic communication.
Certain provisions relating to tax recovery under Rule 225 have also been amended.
These changes form part of the broader effort to streamline the procedural framework under the new Income-tax Rules.
5. Practical Implications for Professionals
The extension provides an important opportunity for Registered Valuers and Authorised Income-tax Practitioners to complete their registration requirements without the pressure of the earlier September 2026 deadline.
Professionals should take the following steps:
- Review their eligibility under Sections 514 and 515 of the Income-tax Act, 2025.
- Examine the revised Forms 169 and 171, as applicable.
- Keep the necessary educational, professional and experience-related documents ready.
- Submit the prescribed registration application within the extended timeline.
- Ensure compliance with all applicable registration conditions.
6. Conclusion
The extension of the registration deadline up to 31 March 2027 is a welcome step by CBDT, providing additional time to Registered Valuers and Authorised Income-tax Practitioners to transition into the regulatory framework introduced under the Income-tax Act, 2025.
The notification not only extends the registration timeline but also introduces revised application forms and certain procedural changes.
Eligible professionals should take advantage of this extended period and complete their registration formalities well before the prescribed deadline to ensure uninterrupted compliance.