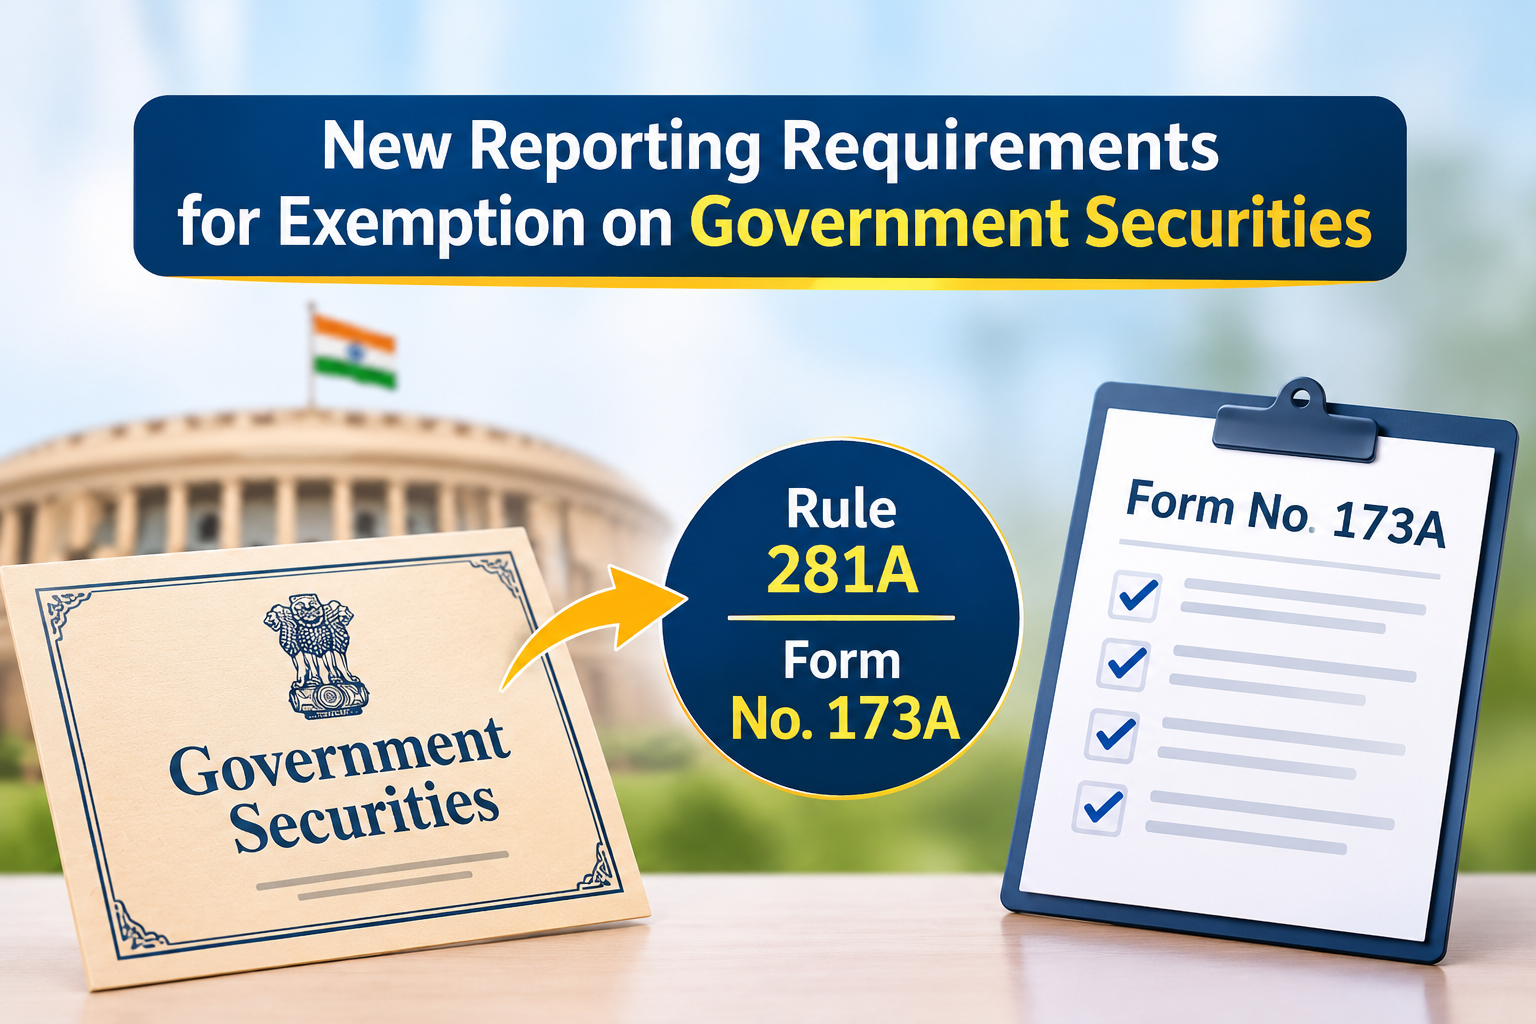
Income-tax (Seventh Amendment) Rules, 2026 introduce Rule 281A and Form No. 173A to strengthen reporting requirements for specified tax-exempt income from Government securities.
The Central Board of Direct Taxes (CBDT) has notified the Income-tax (Seventh Amendment) Rules, 2026, vide Notification No. 137/2026 dated 19 October 2026. The amendment introduces Rule 281A and a new reporting form, Form No. 173A, prescribing additional information requirements for taxpayers claiming exemptions on specified interest income and capital gains arising from Government securities.
This amendment is particularly relevant for foreign investors, Foreign Portfolio Investors (FPIs), institutional investors and other eligible entities dealing in specified Government securities. It aims to strengthen transparency, improve information reporting and facilitate verification of exemption claims by the Income-tax Department.
Key Highlights of the Amendment
The amendment primarily focuses on introducing a structured reporting mechanism for taxpayers claiming exemptions under Schedule IV (Table Sl. Nos. 13D and 13E) of the Income-tax Act, 2025.
1. Introduction of Rule 281A
The newly introduced Rule 281A prescribes the reporting framework and requirements for furnishing information in respect of specified exempt income from Government securities.
The rule establishes a formal mechanism for reporting relevant particulars to substantiate exemption claims and ensure compliance with the applicable provisions of the Income-tax Act, 2025.
2. Introduction of Form No. 173A
CBDT has introduced Form No. 173A to capture additional information relating to taxpayers claiming the specified exemptions.
The form requires relevant particulars, including:
- Taxpayer Information: Name, identification details and country of residence of the assessee.
- PAN and Tax Identification: PAN and applicable foreign tax identification details.
- SEBI Registration Details: Registration particulars of SEBI-registered investors, wherever applicable.
- Government Securities Details: Particulars of the securities in respect of which the exemption is being claimed.
- Income Particulars: Details of exempt interest income and capital gains arising from the specified securities.
The prescribed reporting requirements will help the Income-tax Department maintain a more comprehensive record of exemption claims and the underlying transactions.
Impact on Foreign Investors and Financial Institutions
The amendment assumes particular significance for foreign investors and institutional participants investing in Indian Government securities.
Tax exemptions available under the Income-tax Act, 2025 are subject to prescribed eligibility conditions. However, claiming an exemption also requires appropriate documentation and compliance with the applicable reporting framework.
With the introduction of Form No. 173A, eligible taxpayers will need to ensure that the information relating to their investments, registration status, residential jurisdiction and exempt income is accurately maintained.
Financial institutions, custodians, investment managers and tax advisors may also need to review their existing reporting systems to ensure that the required information is readily available.
Practical Considerations for Chartered Accountants and Tax Professionals
The introduction of Rule 281A and Form No. 173A requires tax professionals to take a more structured approach towards exemption-related compliance.
The following measures should be considered:
1. Review Eligibility: Verify whether the taxpayer and the relevant Government securities qualify for exemption under the specified provisions of Schedule IV.
2. Maintain Investment Records: Reconcile investment statements, transaction records and income details relating to the specified securities.
3. Verify Taxpayer Information: Ensure that PAN, foreign tax identification numbers, residential status and SEBI registration particulars, wherever applicable, are correctly reported.
4. Reconcile Exempt Income: Match the interest income and capital gains reported in the prescribed form with the books of accounts and supporting investment statements.
5. Ensure Timely Compliance: Review the filing procedure and applicable timelines under Rule 281A to avoid reporting errors or procedural non-compliance.
Conclusion
The Income-tax (Seventh Amendment) Rules, 2026 represent another step towards strengthening the reporting and monitoring framework for tax exemptions under the Income-tax Act, 2025. The introduction of Rule 281A and Form No. 173A places greater emphasis on accurate disclosure, proper documentation and transparency in respect of specified Government securities.
For foreign investors, FPIs and other eligible taxpayers, the amendment makes it important to reassess existing compliance procedures and ensure that all prescribed information is appropriately reported.