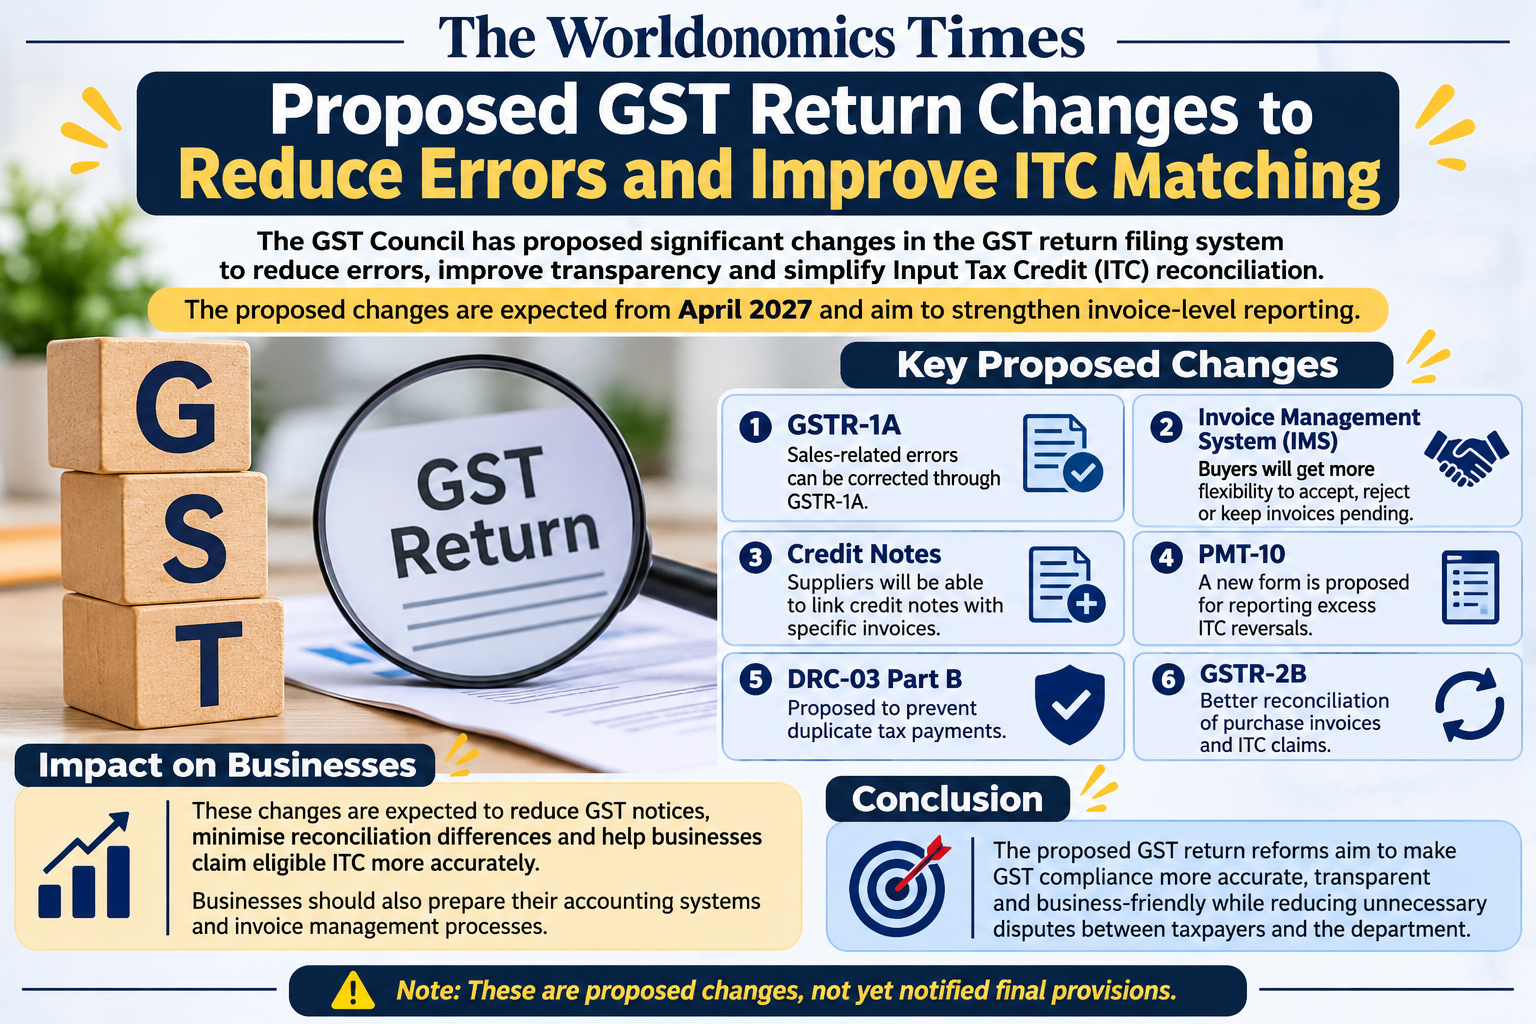
The GST Council has proposed significant changes in the GST return filing system to reduce errors, improve transparency and simplify Input Tax Credit (ITC) reconciliation.
The proposed changes are expected to be implemented from April 2027 and aim to strengthen invoice-level reporting.
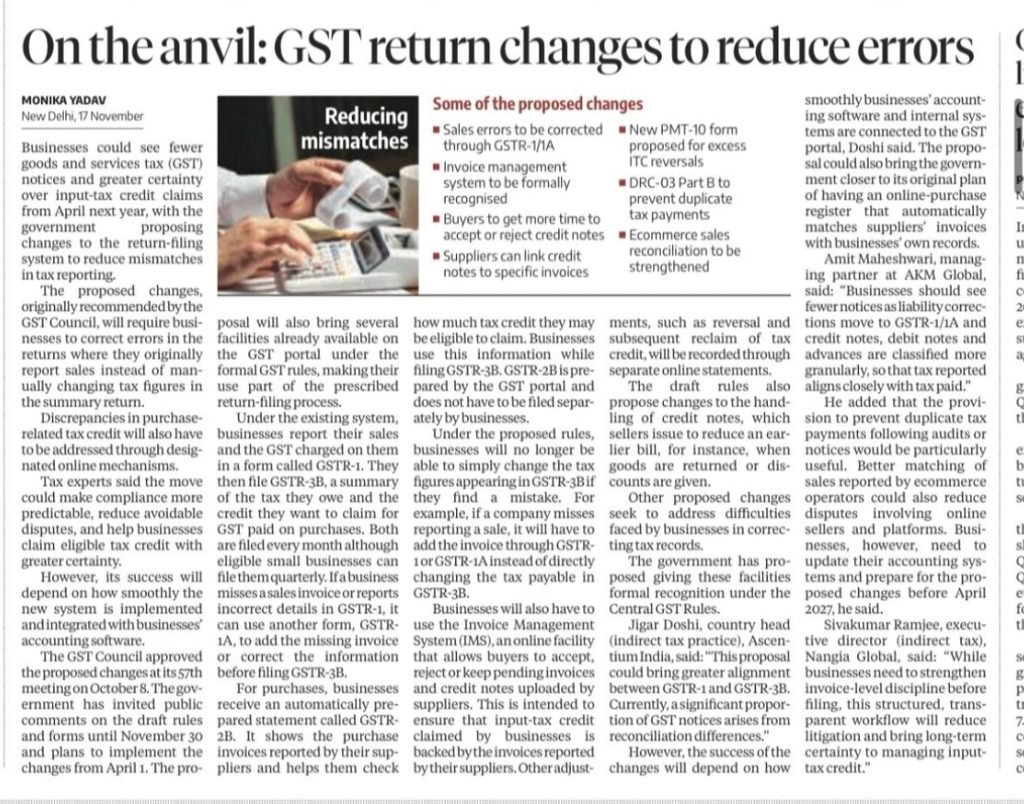
Key Proposed Changes:
GSTR-1A: Sales-related errors can be corrected through GSTR-1A instead of directly changing tax figures in GSTR-3B.
Invoice Management System (IMS): Buyers will get more flexibility to accept, reject or keep invoices pending.
Credit Notes: Suppliers will be able to link credit notes with specific invoices.
PMT-10: A new form is proposed for reporting excess ITC reversals.
DRC-03 Part B: Proposed to prevent duplicate tax payments.
GSTR-2B: Better reconciliation of purchase invoices and ITC claims.
Impact on Businesses
These changes are expected to reduce GST notices, minimise reconciliation differences and help businesses claim eligible ITC more accurately.Businesses should also prepare their accounting systems and invoice management processes to align with the proposed changes.
Conclusion:The proposed GST return reforms aim to make GST compliance more accurate, transparent and business-friendly while reducing unnecessary disputes between taxpayers and the department.
Note: These are proposed changes, not yet notified final provisions.