Introduction: The Illusion of Growth
For decades, revenue growth has been one of the most visible indicators of corporate success. A company reporting higher sales, expanding into new markets and attracting more customers is often perceived as a business moving in the right direction.
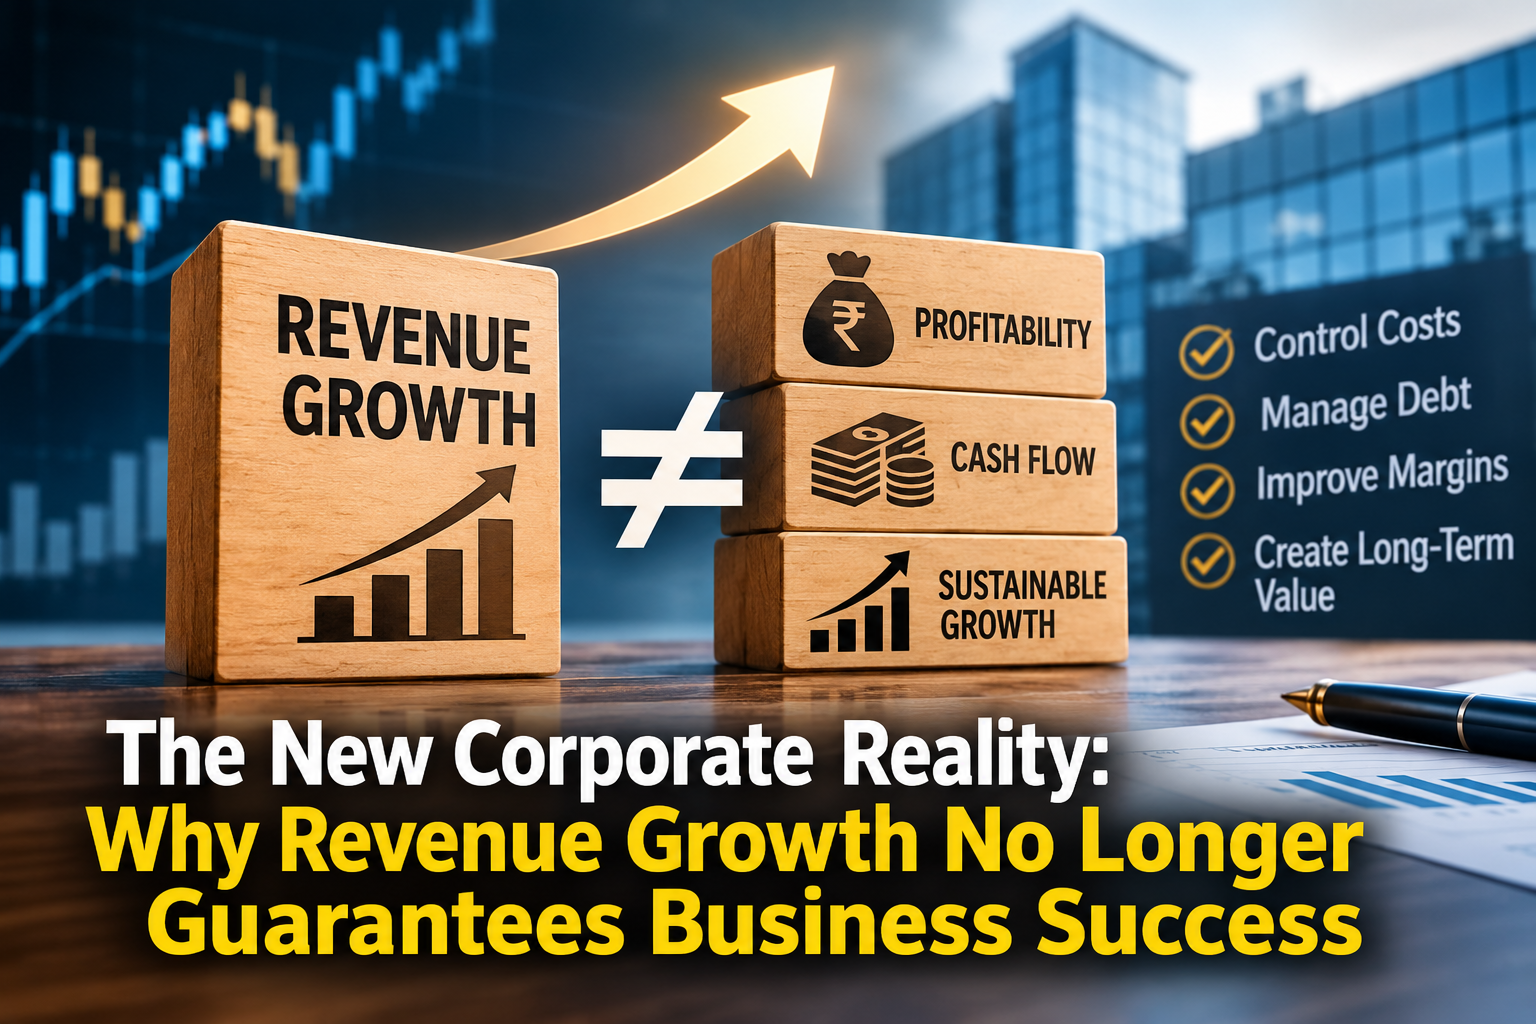
But a fundamental question is increasingly important: what is the value of generating more revenue if a company cannot convert it into profit, cash flow and sustainable returns?
A business can report record sales while facing shrinking margins, rising borrowing costs, mounting debt and a growing dependence on external financing. It can expand its customer base while spending more to acquire each customer. It can even report accounting profits while struggling to pay suppliers, employees and lenders on time.
This is the new corporate reality: growth remains important, but growth without financial discipline can conceal serious weaknesses.
In an environment shaped by competition, technological disruption, changing consumer behaviour and pressure to demonstrate profitability, investors and management teams must look beyond the top line.
The real measure of corporate strength is not simply how much a company sells. It is how efficiently it converts sales into earnings, cash and long-term economic value.
1. Revenue Is the Beginning of the Story, Not the Final Score
Revenue represents the income a company generates from selling goods or services before deducting expenses. It indicates the scale of business activity, but it does not reveal how much value the company retains.
Consider two companies with identical revenue growth but very different cost structures.
ILLUSTRATIVE EXAMPLE — ANNUAL FINANCIAL PERFORMANCE
Company A
₹150 cr
Revenue
Operating costs
₹135 cr
Operating profit
₹15 cr
10% operating margin
Company B
₹150 cr
Revenue
Operating costs
₹145 cr
Operating profit
₹5 cr
3.3% operating margin
Both companies generate the same revenue, but Company A earns three times as much operating profit as Company B.
This illustrates why revenue growth must be assessed alongside operating expenses, profitability and cash generation.
A company can increase sales through discounts, expensive advertising, generous credit terms or aggressive expansion. These strategies may increase revenue without improving the underlying economics of the business.
The key question is not simply whether sales are growing. It is whether each additional rupee of sales contributes enough profit to justify the resources required to generate it.
2. The Margin Problem: When Rising Costs Eat Into Growth
One of the biggest challenges facing companies is the pressure on profit margins.
Raw materials, employee compensation, transportation, electricity, rent, interest expenses and technology investments can all increase the cost of doing business.
If a company cannot pass these higher costs on to customers, revenue growth may coexist with declining profitability.
Recent Indian corporate results illustrate this tension. In July 2026, CRISIL Intelligence estimated that revenue among a sample of more than 400 Indian companies had grown by 11–11.5% year-on-year in the April–June quarter, while higher fuel and freight costs put pressure on margins. The report also noted that price increases contributed to revenue growth, demonstrating that higher sales value does not necessarily mean higher sales volumes.
This creates a difficult balancing act for management.
Raise prices too aggressively, and customers may switch to competitors. Absorb the higher costs, and profit margins may deteriorate. Reduce expenses too sharply, and product quality, service delivery or future growth may suffer.
Successful companies must therefore manage both pricing power and cost efficiency.
Revenue measures how much business a company generates. Margins reveal how effectively it manages the cost of generating that business.
3. The Cash Flow Trap: Profitable on Paper, Struggling in Reality
A company can report accounting profits and still experience a cash shortage.
This happens because revenue recognised in financial statements is not necessarily cash already received from customers.
Imagine a business selling ₹10 crore worth of goods on credit. It records the sales as revenue, but customers may take 60 or 90 days to pay. Meanwhile, the company must pay its employees, suppliers, landlords and lenders.
If the business expands rapidly while collections remain slow, its working-capital requirements increase.
The company may need additional bank loans simply to finance its own growth.
A 2026 study published in the International Review of Economics & Finance, examining European small and medium-sized enterprises over 2012–2022, found that working-capital investment has an optimal range: both insufficient and excessive investment can hurt profitability, particularly for financially constrained businesses.
This is a crucial lesson for growing companies.
- More sales can create more unpaid invoices.
- More inventory can tie up additional cash.
- Longer customer credit periods can delay collections.
- Faster expansion can increase the need for external financing.
Consequently, cash flow from operating activities deserves as much attention as reported profit.
A business that consistently generates cash from its operations has greater flexibility to invest, repay debt and withstand economic uncertainty.
4. The Debt Dilemma: Growth Can Become Expensive
When internal cash generation is insufficient, companies often turn to borrowing.
Debt can be a productive financial tool. It can fund machinery, technology, factories, distribution networks and other investments that generate returns above their financing costs.
The problem arises when borrowing finances expansion that fails to deliver sufficient returns.
Interest payments are contractual obligations. They must be met even when sales disappoint, input costs rise or customers delay payments.
Consider a business that borrows heavily to expand production capacity. If demand grows more slowly than expected, the company may be left with underutilised facilities, high fixed costs and substantial interest expenses.
Revenue may still increase, but profitability and financial stability can deteriorate.
This is why financial analysis must examine not only how quickly a company is growing, but also how that growth is financed.
Useful indicators include the interest coverage ratio, net debt, debt-to-equity ratio and operating cash flow. These help investors and management assess whether expansion is strengthening the business or increasing its financial vulnerability.
5. The Customer Acquisition Illusion: More Customers Do Not Always Mean More Value
Digital businesses and consumer-facing companies often pursue growth through advertising, discounts, promotional offers and subsidised services.
These strategies can attract customers quickly, but the economics become questionable when acquiring and serving each customer costs more than the revenue they generate over time.
For example, a company may offer steep discounts to increase orders and expand market share. Sales volumes rise, but the business remains dependent on promotional spending to retain customers.
If customers leave as soon as discounts disappear, the apparent growth may be less durable than it appears.
Management must therefore evaluate customer acquisition cost, customer retention, repeat purchases, contribution margin and lifetime customer value.
The same principle applies beyond digital businesses. A manufacturer that wins customers by underpricing competitors or a retailer that expands through persistent discounting can increase revenue without building a sustainable competitive advantage.
Growth is valuable when it produces lasting customer relationships and positive unit economics — not merely when it increases transaction volumes.
6. Why the Indian Corporate Landscape Makes This Debate Important
India’s economic expansion creates substantial opportunities for businesses. Rising consumption, infrastructure investment, digital adoption and industrial development can support new markets and increased demand.
However, strong economic growth does not guarantee equally strong earnings growth for every company.
A Reuters analysis published on November 1, 2026, highlighted a disconnect between India’s broader economic growth and corporate profit performance. It pointed to input-cost pressures, competition and limited pricing power as factors weighing on corporate earnings. The analysis also noted that AI is changing demand conditions for technology-services companies.
These pressures affect businesses differently.
Manufacturers may struggle when commodity prices rise faster than selling prices. Retailers may face higher distribution costs and intense competition. IT services companies may need to adapt their pricing and delivery models as AI changes how work is performed. Consumer businesses may find it difficult to increase prices when households are sensitive to costs.
The common factor is the gap between market opportunity and financial execution.
Companies must convert demand into profitable sales, control operating expenses, collect payments efficiently and allocate capital to investments that generate adequate returns.
In such an environment, growth quality becomes as important as growth speed.
7. How Should Investors and Management Evaluate Corporate Success?
A more complete evaluation requires looking beyond a single headline figure.
| Financial indicator | What it helps reveal |
|---|---|
| Revenue growth | Whether the business is expanding |
| Operating profit margin | How efficiently sales are converted into operating profit |
| Net profit margin | How much profit remains after expenses, interest and taxes |
| Operating cash flow | Whether the core business generates cash |
| Return on invested capital (ROIC) | Whether the company earns adequate returns on the capital employed |
| Working-capital cycle | How efficiently cash moves through inventory, sales and collections |
| Debt and interest coverage | Whether borrowing levels are financially sustainable |
| Free cash flow | How much cash remains after capital expenditure |
These indicators should be assessed together and over multiple periods.
For example, rising revenue accompanied by stable margins, healthy cash generation and improving returns on invested capital generally presents a stronger picture than rising revenue accompanied by falling margins, increasing receivables and higher debt.
There is no single ratio that can establish whether a business is successful. Industry characteristics, investment cycles, accounting policies and the company’s stage of development all matter.
A young business may reasonably prioritise expansion over immediate profitability. A capital-intensive manufacturer may experience temporary cash-flow pressure while building a new plant. What matters is whether the strategy has a credible economic rationale and whether financial performance develops in line with expectations.
8. The Strategic Shift: From Growth at Any Cost to Profitable Growth
The new corporate reality does not mean that companies should stop expanding. It means that expansion must be supported by stronger financial discipline.
Businesses can improve the quality of growth by focusing on several priorities.
Strengthen pricing and cost management. Understand which products and customers generate genuine contribution, and avoid pursuing sales that systematically destroy value.
Improve working-capital efficiency. Monitor collections, negotiate appropriate supplier terms and avoid excessive inventory accumulation.
Allocate capital carefully. Evaluate new projects against expected returns, financing costs and realistic demand assumptions.
Use technology to improve productivity. Investments in automation and AI should produce measurable operational benefits rather than simply add to technology expenditure.
Measure long-term value creation. Management incentives should consider cash generation, profitability and returns on capital alongside revenue growth.
The objective is not to maximise this quarter’s earnings at the expense of future opportunity. It is to ensure that today’s expansion creates a financially stronger business tomorrow.
Conclusion: Growth Is a Strategy, Not Proof of Success
Revenue growth remains an important indicator of business progress, but it is not a complete measure of corporate health.
A company can sell more while earning less, expand while accumulating debt, report profits while facing cash shortages and attract customers without establishing sustainable demand.
These contradictions explain why financial performance must be evaluated through a broader lens.
The strongest businesses are not necessarily those that grow the fastest. They are those that can translate growth into durable earnings, generate cash consistently, allocate capital intelligently and withstand changes in market conditions.
For investors, this means looking beyond sales figures. For management teams, it means prioritising the economics behind every expansion decision. For the wider economy, it means recognising that corporate growth creates lasting value only when it improves productivity, financial resilience and the efficient use of resources.
In the new corporate reality, the decisive question is no longer just how fast a company grows. It is whether that growth makes the company genuinely stronger.