A company may report impressive revenue growth, maintain apparently healthy financial statements and receive an unqualified audit opinion. Yet, beneath these numbers, financial irregularities, fictitious transactions or deliberate fund diversion may remain concealed.
Corporate financial fraud is rarely limited to a simple accounting error. It can involve complex transactions, manipulated records, undisclosed related-party dealings and deliberate misrepresentation of financial performance.
This raises an important question: Are traditional auditing mechanisms sufficient to identify increasingly sophisticated corporate frauds?
The growing relevance of forensic accounting suggests that the answer may require a different approach.
1. When Financial Statements Tell Only Half the Story
Traditional financial audits primarily focus on obtaining reasonable assurance that financial statements are free from material misstatement, whether caused by fraud or error.
However, a forensic investigation has a different objective.
It examines financial information with the intention of identifying suspicious transactions, tracing the movement of funds, establishing financial relationships and collecting evidence that may support legal or regulatory proceedings.
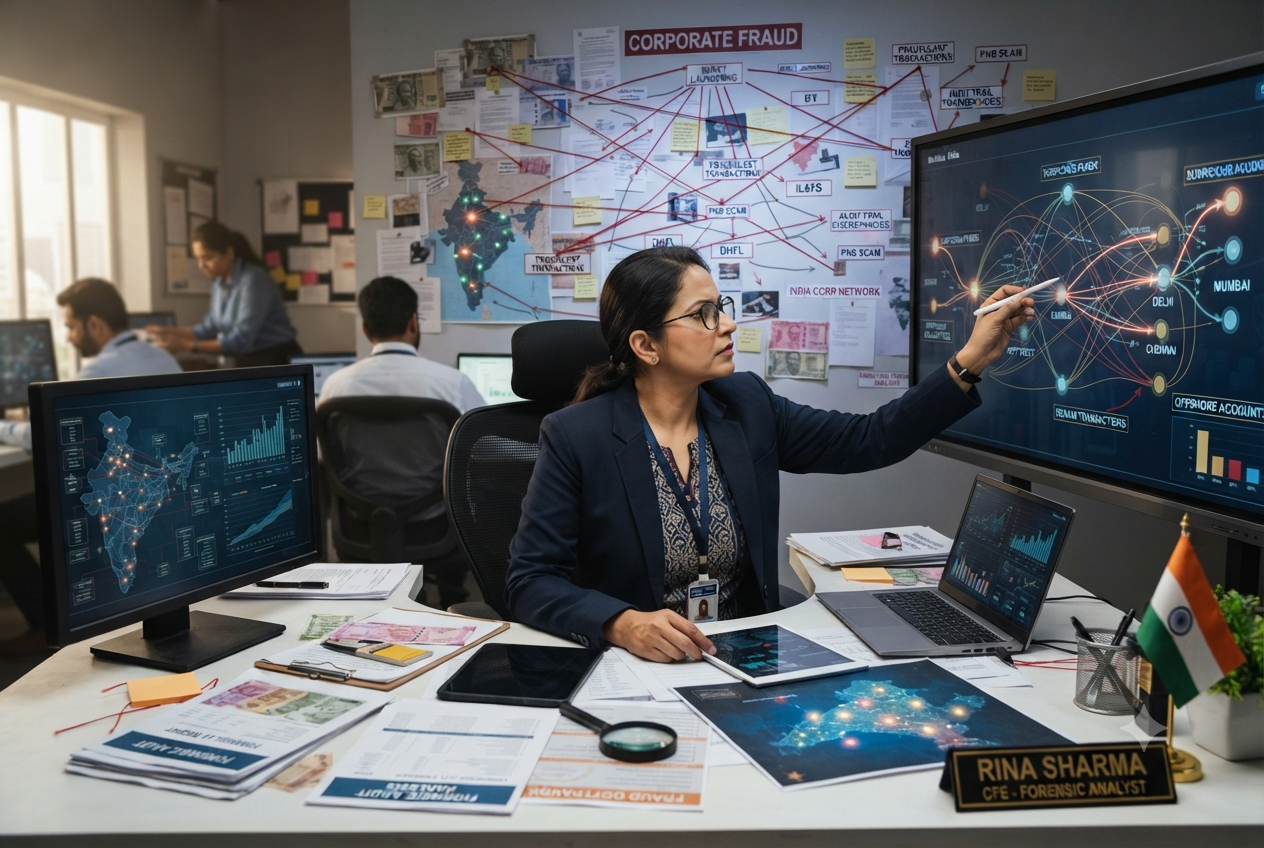
For example, an organisation may record substantial sales through questionable transactions involving related entities. While the reported revenue may appear legitimate on paper, examining bank movements, customer confirmations, transaction patterns and supporting documentation may reveal inconsistencies.
The distinction is important: an audit examines financial statements, whereas a forensic investigation follows the evidence behind suspicious financial activity.
2. How Forensic Accounting Detects Financial Manipulation
Forensic accounting combines accounting knowledge, auditing techniques, investigation and data analytics.
Some important techniques include:
Benford’s Law: Examining the frequency distribution of leading digits in numerical datasets to identify unusual patterns that may warrant further investigation.
Transaction Analysis: Identifying unusual payments, duplicate invoices, round-number transactions and suspicious fund transfers.
Related-Party Investigation: Examining transactions between connected entities to identify potential conflicts of interest or artificial business arrangements.
Digital Forensics: Analysing electronic records, metadata, communications and digital evidence to reconstruct financial activities.
Fund Tracing: Following the movement of money across multiple accounts and entities to identify possible diversion or concealment.
These techniques do not automatically establish fraud. They help investigators identify anomalies, develop investigative hypotheses and obtain corroborating evidence.
3. India’s Institutional Framework: Who Investigates Corporate Fraud?
India already has institutional mechanisms to investigate corporate financial misconduct.
The Serious Fraud Investigation Office (SFIO), established under Section 211 of the Companies Act, 2013, is a multidisciplinary organisation operating under the Ministry of Corporate Affairs.
Its expertise includes accountancy, forensic auditing, banking, taxation, information technology, company law and capital markets.
Section 212 provides the framework for assigning investigations into company affairs to the SFIO.
Similarly, the National Financial Reporting Authority (NFRA), established under Section 132 of the Companies Act, plays an important role in monitoring compliance with accounting and auditing standards and overseeing audit quality within its statutory jurisdiction.
These institutions demonstrate that corporate financial accountability requires coordination between accounting expertise, regulatory oversight and investigative capabilities.
4. The Regulatory Question: Does India Need Stronger Forensic Audit Standards?
An important development in India’s professional accounting landscape is the introduction of Forensic Accounting and Investigation Standards (FAIS) by ICAI, effective from 1 July 2023 for relevant engagements undertaken by its members.
These standards address areas such as fraud risk assessment, engagement planning, evidence collection, digital investigation, reporting and quality control.
However, a broader regulatory concern remains.
In an opinion published in May 2026, Mint highlighted that forensic audit engagements are increasingly used in corporate fraud investigations and insolvency proceedings, while the standards governing these engagements do not have the same statutory enforceability as notified financial auditing standards.
This raises questions about professional qualifications, accountability, consistency in investigation procedures and the reliability of forensic reports.
A stronger and more harmonised framework could help ensure that forensic investigations are conducted with appropriate independence, professional competence and evidentiary discipline.
5. Why This Matters for Investors, Lenders and Companies
The implications of financial fraud extend beyond the organisation involved.
For investors, financial manipulation can distort valuation and lead to incorrect investment decisions.
For banks and financial institutions, undiscovered fund diversion can increase credit risk and contribute to non-performing assets.
For employees and suppliers, corporate financial misconduct can threaten business continuity and employment.
For the wider economy, repeated failures in financial accountability can weaken investor confidence and increase the cost of capital.
Consequently, forensic accounting should not be viewed merely as a post-fraud investigation mechanism. It can also contribute to stronger internal controls, improved risk management and early identification of financial irregularities.
6. The Emerging Role of Finance Professionals
The changing corporate environment is expanding the responsibilities of accounting and finance professionals.
Beyond financial reporting and compliance, organisations increasingly need professionals who understand financial data, identify unusual transaction patterns, evaluate internal controls and investigate potential irregularities.
Forensic accounting therefore creates an important intersection between accounting, costing, auditing, financial management, law and technology.
The ability to interpret financial information critically, rather than simply prepare or verify it, is becoming increasingly valuable.
Conclusion: From Financial Reporting to Financial Truth
The credibility of a corporate organisation cannot be measured solely by the financial statements it publishes. It must also be assessed by the integrity of the transactions, controls and decisions underlying those statements.
Traditional auditing remains essential to financial accountability. However, complex financial misconduct requires specialised investigative techniques, technological capabilities and stronger institutional coordination.
Forensic accounting offers an important bridge between financial information and financial evidence.
Ultimately, the objective should not simply be to identify fraud after losses have occurred, but to build a corporate environment in which financial manipulation becomes increasingly difficult to conceal.
Because in the world of finance, the real challenge is not merely to verify the numbers, but to uncover the truth behind them.