Making India’s capital markets more accessible, one digital verification at a time
In an increasingly connected financial world, geography should not become an unnecessary barrier to investment. Yet, for many Non-Resident Indians (NRIs), Overseas Citizens of India (OCIs) and foreign investors, completing Know Your Customer (KYC) formalities while living overseas has often involved documentation, verification and procedural challenges.
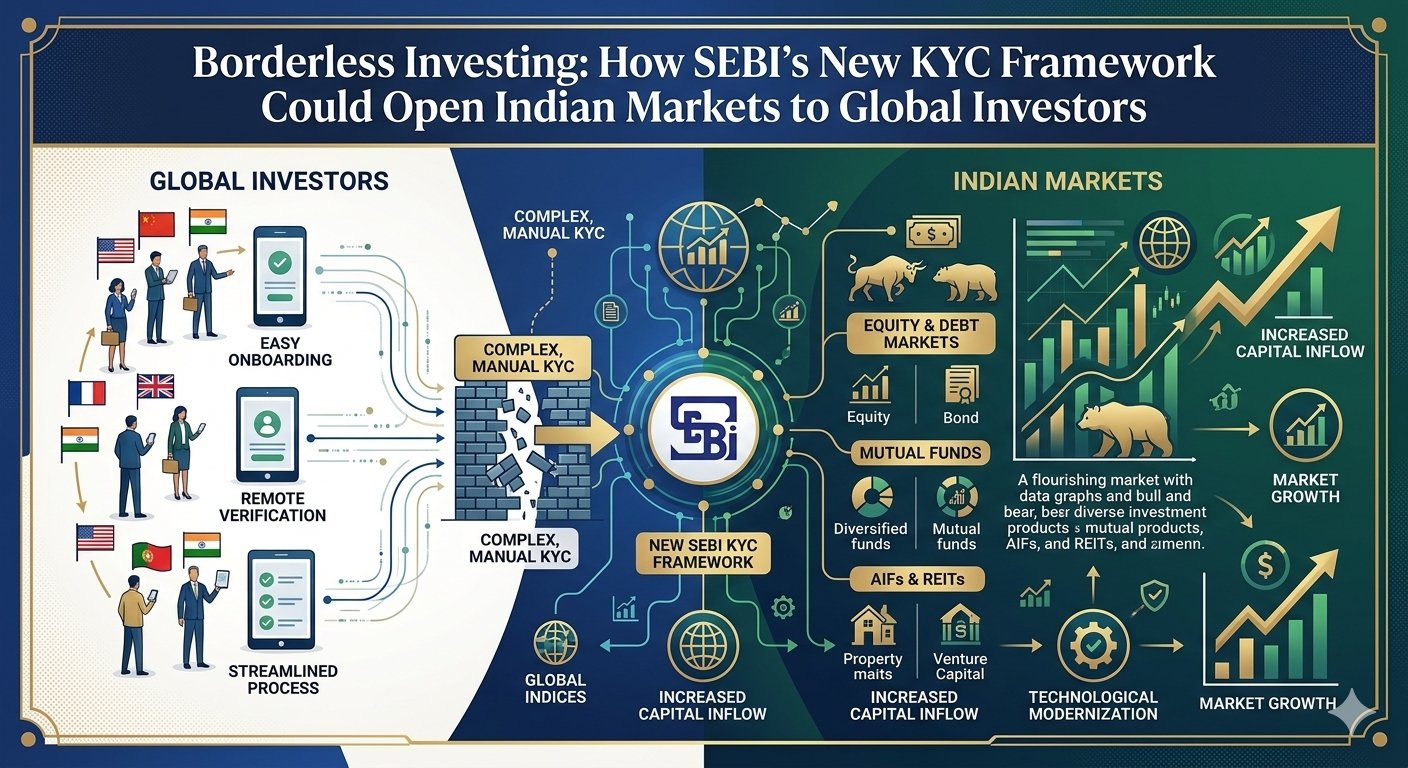
India’s securities market regulator, the Securities and Exchange Board of India (SEBI), has taken a step towards addressing this challenge by relaxing digital KYC requirements for eligible overseas investors.
The revised framework, effective 3 December 2026, allows eligible individuals residing in FATF-compliant countries to complete digital onboarding without being physically present in India.
What has changed?
Under the revised framework, eligible persons resident outside India can submit KYC information and supporting documents digitally while residing overseas.
The changes also introduce greater portability of KYC records across financial intermediaries. This means investors may not need to repeat the entire verification process when moving between eligible intermediaries, subject to applicable validation and due-diligence requirements.
SEBI has also clarified that intermediaries retain ultimate responsibility for ensuring compliance with KYC requirements.
Why does KYC portability matter?
Consider an NRI who already has a verified KYC record with one securities-market intermediary but wants to open an account with another.
Under a more portable framework, verified information can be relied upon rather than requiring the investor to restart the process from scratch.
This can potentially deliver three important benefits:
- Lower compliance friction: Less repetitive documentation for eligible investors.
- Improved accessibility: Overseas investors can complete onboarding without travelling to India.
- Better operational efficiency: Financial intermediaries can reduce duplication while maintaining regulatory checks.
Technology and security go hand in hand
Simplifying onboarding does not mean compromising investor protection.
SEBI’s framework includes safeguards such as live video verification, facial liveness checks, GPS coordinates, timestamps and controls against spoofed IP addresses and proxy servers.
Intermediaries must also verify relevant identity documents and retain responsibility for enhanced due diligence based on the investor’s risk profile.
The framework therefore attempts to balance convenience with the integrity of India’s financial markets.
What could this mean for India’s capital markets?
A smoother onboarding experience may improve the ease with which eligible overseas investors access India’s securities market.
For the financial services industry, this could encourage intermediaries to strengthen digital infrastructure, improve cross-border client servicing and develop more efficient compliance systems.
However, easier KYC should not be confused with automatic investment eligibility. Investors must continue to comply with applicable FEMA, tax, account-opening and securities-market requirements.
The bigger picture
India’s financial-market development is not determined only by market capitalisation, trading volumes or the number of listed companies. The quality of its institutional infrastructure matters equally.
A market that is easier to access, more efficient to operate and secure in its verification processes is better positioned to attract long-term participation.
SEBI’s revised KYC framework is a step in that direction. Its real success will depend on how effectively intermediaries implement the changes while preserving investor protection.
The future of financial markets will not just be about who can invest, but how seamlessly and securely they can participate.