The International Monetary Fund is urging governments to strengthen international economic cooperation, maintain fiscal stability and reinforce financial resilience as the global economy faces growing uncertainty. With geopolitical tensions, rising public debt, inflationary pressures and changing trade relationships challenging economic stability, coordinated policy action is becoming increasingly important for sustainable long-term growth.
Global Economy Faces Growing Challenges
International economic cooperation has become a central priority as countries navigate an increasingly uncertain global environment. Economic shocks are no longer confined within national borders. Conflicts, energy-market disruptions, trade restrictions and financial instability can quickly spread across regions, affecting businesses, investors, governments and households.
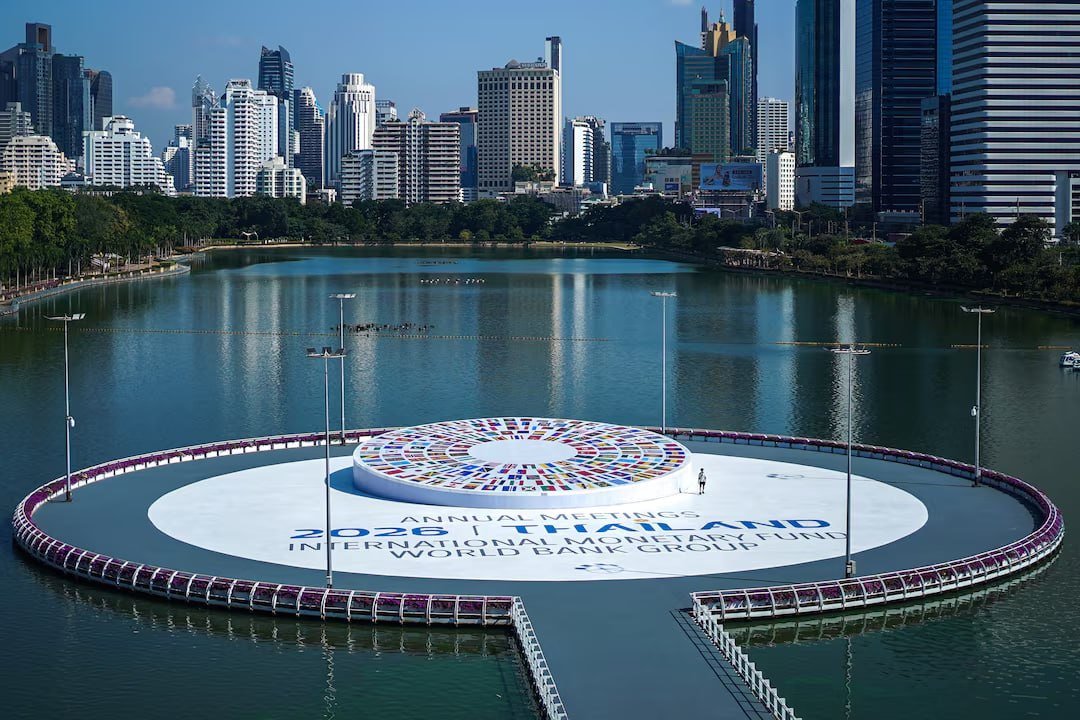
In its October 2026 World Economic Outlook, the International Monetary Fund (IMF) highlighted that the global economy remains resilient but that this resilience is becoming increasingly uneven. The IMF projects global economic growth of 3.1% in 2026, followed by a moderate improvement to 3.4% in 2027.
However, the outlook remains exposed to significant downside risks, including geopolitical conflicts, renewed trade tensions, fiscal vulnerabilities and uncertainty surrounding investment in artificial intelligence.
The IMF’s message is clear: countries must move beyond short-term crisis management and establish stronger economic foundations through responsible policies and international cooperation.
Fiscal Stability Becomes a Global Priority
One of the IMF’s major concerns is the growing fiscal pressure facing governments. Public debt has increased in many economies following years of emergency spending, economic support programmes, higher borrowing costs and repeated global disruptions.
As interest payments consume a larger share of government budgets, countries have less flexibility to invest in infrastructure, education, healthcare and other development priorities.
The IMF is therefore encouraging governments to rebuild fiscal buffers and establish credible medium-term plans to manage public finances. This includes improving revenue collection, reviewing public expenditure and ensuring that borrowing supports productive economic activity.
Fiscal discipline does not necessarily mean reducing all government spending. Rather, it requires prioritising investments that improve productivity and generate long-term economic benefits.
Governments must also ensure that temporary support measures are carefully targeted. Broad subsidies and poorly designed financial assistance can place additional pressure on public budgets without addressing the underlying causes of economic difficulties.
Financial Resilience Essential for Stability
The stability of the global financial system is another important part of the IMF’s recommendations. International markets remain interconnected, meaning financial stress in one major economy can affect banking systems, currency markets and investment flows elsewhere.
The IMF’s October 2026 Global Financial Stability Report noted that financial markets have remained resilient despite multiple shocks, but warned that important risks remain elevated.
Potential vulnerabilities include rising sovereign bond yields, high public debt, excessive optimism surrounding artificial intelligence investments and cyber incidents that could disrupt financial services.
Strengthening financial resilience requires effective regulation, transparent financial institutions, responsible lending practices and better monitoring of emerging risks.
Central banks must also remain focused on maintaining price stability while communicating monetary policy decisions clearly. Their independence is important for building confidence among investors, businesses and households.
A resilient financial system should be capable of absorbing economic shocks without allowing temporary disruptions to develop into widespread financial crises.
International Cooperation Can Reduce Trade and Supply-Chain Risks
Trade cooperation is particularly important as global supply chains face repeated disruptions. Changes in tariffs, restrictions on essential commodities and geopolitical tensions can increase production costs and weaken international business confidence.
The IMF has emphasised the importance of transparent and predictable trade rules. Countries should work towards reducing unnecessary barriers while maintaining open communication on trade and investment policies.
Cooperation is also essential in areas such as energy security, food supplies, critical minerals and advanced technologies. No single country can independently manage every risk associated with global production networks.
For developing economies, predictable international trade conditions can encourage investment, improve access to technology and create opportunities for employment and industrial development.
Stronger cooperation can also help prevent economic fragmentation, where countries increasingly divide into competing trade and financial groups. Such fragmentation could reduce efficiency, increase costs and weaken long-term global growth.
Developing Economies Need Greater Support
Emerging and developing economies face particular difficulties because they often have limited fiscal resources and greater exposure to external economic shocks.
Higher international interest rates can increase the cost of borrowing, while currency depreciation makes imported fuel, food and machinery more expensive. Countries dependent on commodity imports may also experience pressure on their foreign exchange reserves.
The IMF has highlighted the importance of strengthening domestic institutions, improving public financial management and supporting structural reforms.
International financial cooperation can help vulnerable countries manage debt challenges, improve access to financing and strengthen their ability to respond to future crises.
For countries such as India, stronger cooperation can support trade diversification, infrastructure development, technology investment and energy security. Continued investment in domestic manufacturing, digital infrastructure and renewable energy can also improve economic resilience.
However, developing economies need sufficient policy flexibility to pursue their own growth priorities while maintaining responsible fiscal and monetary frameworks.
Technology and Energy Cooperation Will Shape Future Growth
Artificial intelligence, digital infrastructure and clean energy are creating new opportunities for productivity and economic transformation. At the same time, the benefits and risks of these developments are not distributed equally across countries.
The IMF has identified AI-related investment as an important source of potential growth, while warning that concentrated supply chains and unrealistic market expectations could create vulnerabilities.
International cooperation can help establish appropriate technology standards, strengthen cybersecurity and encourage responsible innovation.
Energy cooperation is equally important. Investment in renewable energy, reliable electricity networks and diversified supply sources can reduce vulnerability to geopolitical disruptions and volatile commodity prices.
Countries that combine technological progress with strong institutions and long-term investment strategies are likely to be better positioned to benefit from future economic opportunities.
The Road Ahead
The global economy is entering a period in which resilience will depend not only on national economic strength but also on the ability of countries to work together.
Governments must strengthen public finances, financial institutions and domestic supply chains while maintaining open channels of international dialogue.
The IMF’s recommendations highlight that sustainable growth requires a coordinated approach involving fiscal responsibility, monetary stability, predictable trade policies and structural reforms.
The Worldonomics Times View
The Worldonomics Times believes that stronger international economic cooperation is no longer optional; it is essential for maintaining stability in an interconnected global economy.
The challenges facing the world cannot be resolved through isolated national policies alone. Rising public debt, financial market volatility, geopolitical tensions and supply-chain disruptions require governments to work together while maintaining responsible domestic economic management.
Fiscal stability must remain a priority, but it should not come at the expense of productive investment and social development. Governments need to spend more effectively, protect vulnerable communities and direct public resources towards infrastructure, education, technology and energy security.
Similarly, international cooperation should focus on practical outcomes rather than declarations. Transparent trade rules, coordinated financial safeguards, improved debt-management frameworks and cooperation on critical technologies can deliver meaningful benefits.
Developing economies must also have a stronger voice in international financial discussions. Their participation is essential to creating a global economic system that supports inclusive growth rather than widening existing inequalities.
The Worldonomics Times believes that the future of global growth will depend on a simple but powerful principle: national economic strength and international cooperation must advance together. A more stable, resilient and inclusive world economy can only be built through shared responsibility and long-term commitment.