The Worldonomics Times | Taxation & Business
New Delhi, October 27, 2026
India is preparing to introduce a fresh set of Goods and Services Tax (GST) process reforms from November 1, 2026, aimed at simplifying registration procedures, reducing documentation-related difficulties and improving the ease of doing business. The reforms follow the recommendations of the 57th GST Council meeting held on October 8, 2026, and form part of the government’s broader efforts to make indirect tax administration more transparent, predictable and taxpayer-friendly.
The proposed changes are particularly significant for small businesses, start-ups, traders and sellers operating through e-commerce platforms. By streamlining registration applications and clarifying documentary requirements, the government aims to reduce unnecessary correspondence between taxpayers and tax officers and facilitate faster processing of applications.
Standardised Documentation to Improve Registration
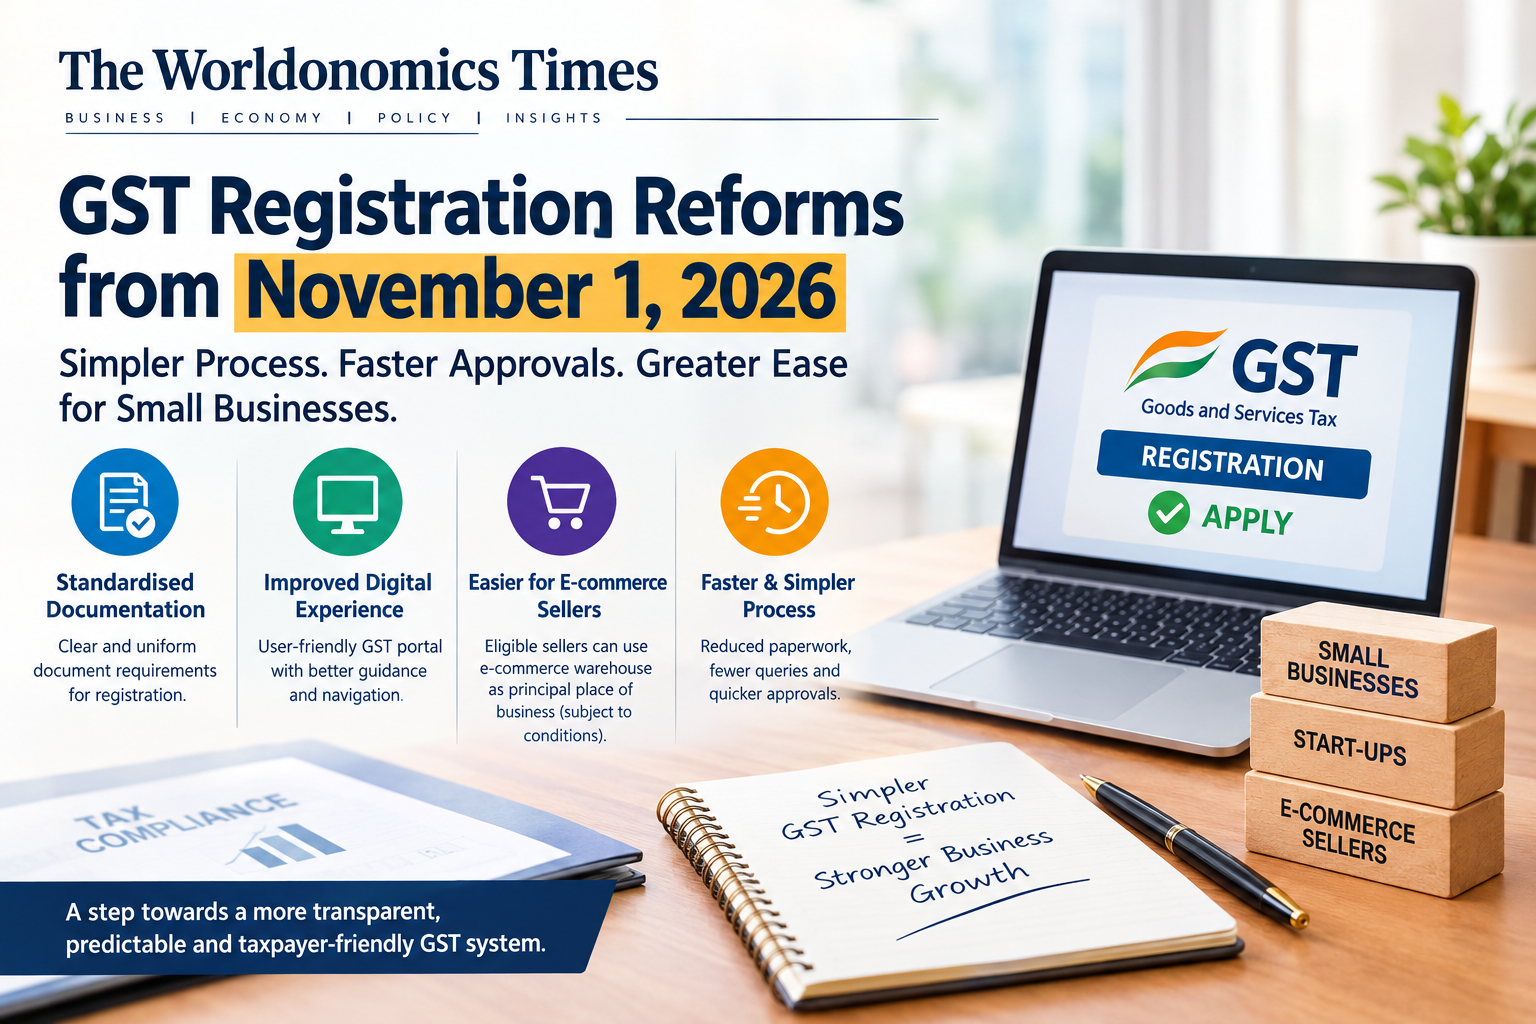
One of the key developments is the move towards comprehensive and standardised documentation for GST registration. Applicants frequently face delays because of incomplete applications, inconsistent supporting documents or uncertainty about the evidence required to establish a place of business.
Under the proposed framework, the Central Board of Indirect Taxes and Customs (CBIC) is providing clearer guidance on the documents and information required for registration. Prescribed formats for consent letters, affidavits and undertakings, together with frequently asked questions, are intended to improve consistency in the application process.
The GST registration form, GST REG-01, is also expected to become more user-friendly, incorporating clearer document-selection options and improved guidance. These measures should help applicants understand their obligations before submitting an application and reduce avoidable queries from tax officers.
The initiative reflects a broader policy objective: registration should be based on clear, uniform requirements rather than uncertainty over documentation.
Improved Digital Experience for Taxpayers
The GST portal is expected to provide a more intuitive registration experience through clearer navigation, drop-down lists, tooltips and contextual instructions. A better-designed application process can help businesses identify missing information and submit the correct documents at the outset.
For small enterprises without dedicated tax departments, these improvements could be particularly valuable. They may reduce the time and professional costs associated with repeated corrections, clarification requests and resubmissions.
However, applicants must continue to provide accurate information and genuine supporting documents. Simplification of procedures does not remove statutory eligibility conditions, verification requirements or the responsibility to comply with the CGST Act and applicable rules.
Easier GST Registration for Small E-commerce Sellers
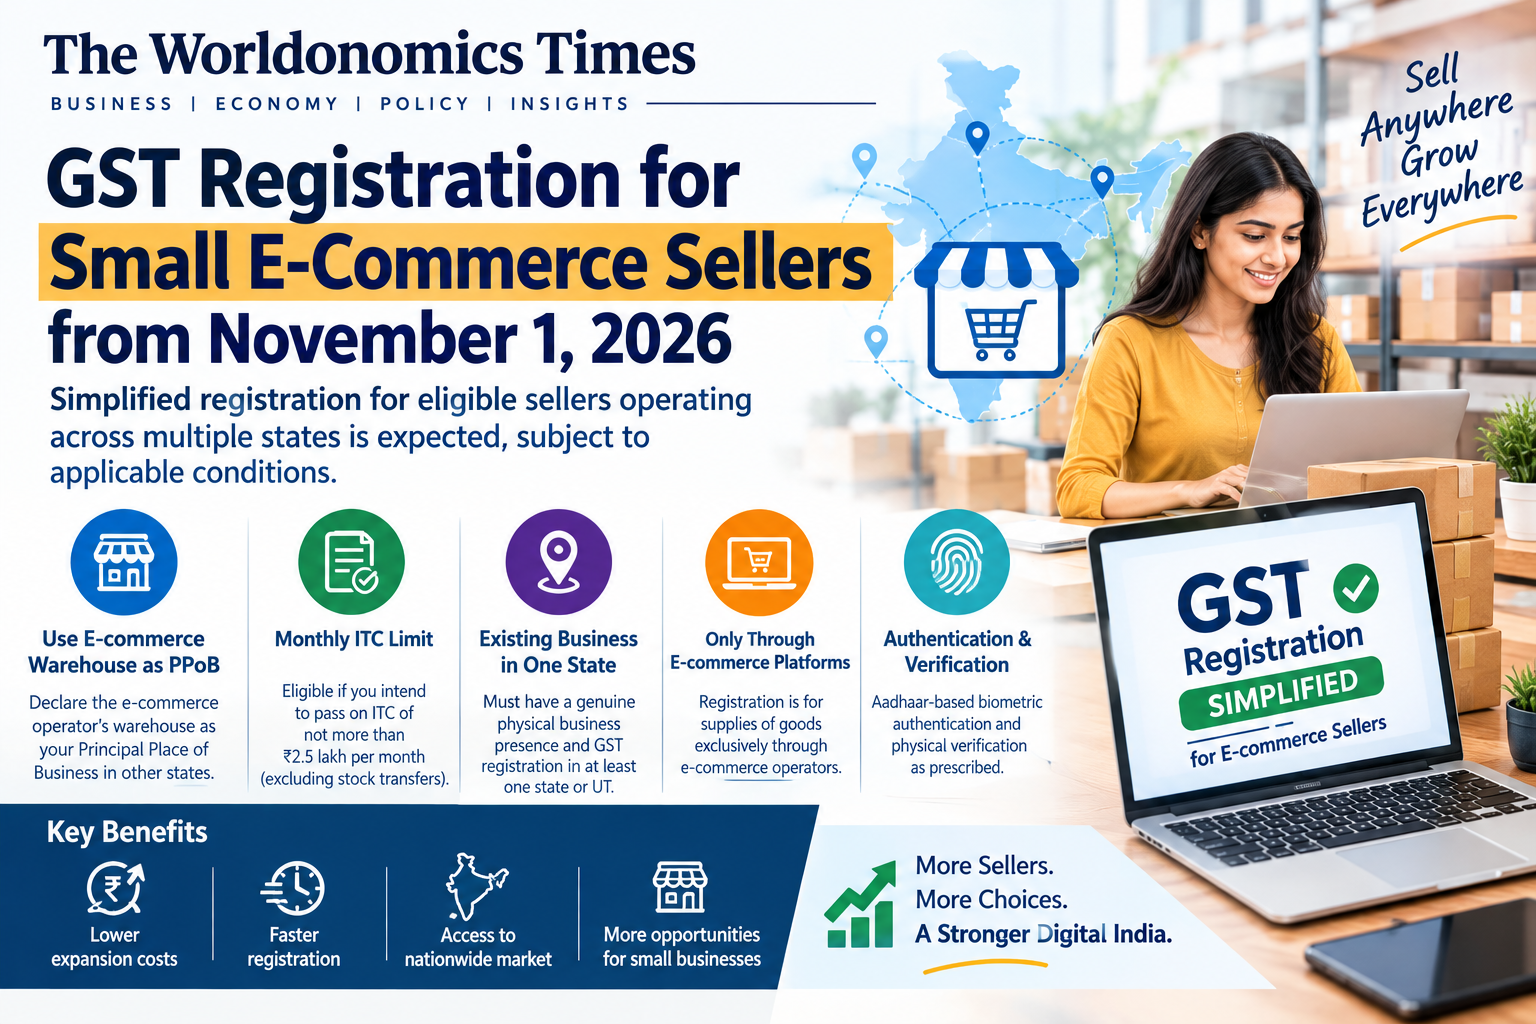
Another important measure concerns small suppliers selling goods through e-commerce operators across multiple states and Union Territories.
Under the proposed arrangements, eligible sellers may be permitted to declare an e-commerce operator’s warehouse as their Principal Place of Business in a state or Union Territory where they store goods, even when they do not maintain a separate physical establishment there. The arrangement is subject to prescribed conditions, including the applicable input tax credit limit and the consent of the e-commerce operator.
The seller would still need to establish a genuine business presence in one state, where applicable authentication and physical verification requirements would be completed. Registrations in other eligible jurisdictions could then be facilitated without requiring the same level of separate officer intervention.
This measure could help smaller sellers expand their market reach without establishing independent offices in every state where their goods are stored. It may also reduce the administrative and infrastructure costs associated with interstate e-commerce operations.
Businesses should nevertheless verify the final conditions and applicable notifications before relying on this facility.
Expected Benefits for Businesses and Professionals
The registration reforms could deliver several practical benefits:
- Reduced paperwork: Standardised document requirements should make applications easier to prepare.
- Fewer avoidable queries: Clearer instructions may reduce clarification requests and application rejections.
- Lower compliance costs: Small businesses may spend less time correcting registration applications.
- Improved market access: Eligible e-commerce sellers may find interstate expansion easier.
- Greater predictability: Uniform documentation and clearer procedures can help businesses plan registration timelines more effectively.
For Chartered Accountants, Cost and Management Accountants, tax practitioners and corporate finance teams, these changes also underline the importance of updating registration checklists and advising clients on the revised requirements.
What Should Taxpayers Do Now?
Businesses planning a new registration or an expansion into additional states should review their documentation, confirm their principal place of business and ensure that address proofs, authorisations and consent documents are consistent.
E-commerce sellers should additionally review their warehouse arrangements, platform agreements and eligibility under the applicable conditions. Existing taxpayers should not assume that every new registration facility automatically changes their current registration obligations.
Tax professionals should monitor CBIC notifications, circulars and GST Portal advisories to determine the exact effective dates and operational requirements.
Conclusion
The GST registration reforms expected from November 1, 2026, represent an important step towards a simpler and more predictable tax administration system. Standardised documentation, improved digital guidance and easier registration arrangements for eligible e-commerce sellers could reduce compliance friction and support the growth of small businesses.
The ultimate success of these reforms will depend on consistent implementation, clear communication and effective grievance redressal. For taxpayers, the immediate priority is to understand the final notified provisions and ensure that every registration application remains accurate, complete and compliant with the law.
Editorial note: This article is based on reported GST reform measures and official GST Council recommendations available as of October 27, 2026. The applicable CBIC notifications and circulars should be consulted for the final legal position and effective dates.