By: CA Sangam Kumar Aggarwal | Worldonomics Times
A significant step towards strengthening India’s IFSC aircraft-leasing ecosystem
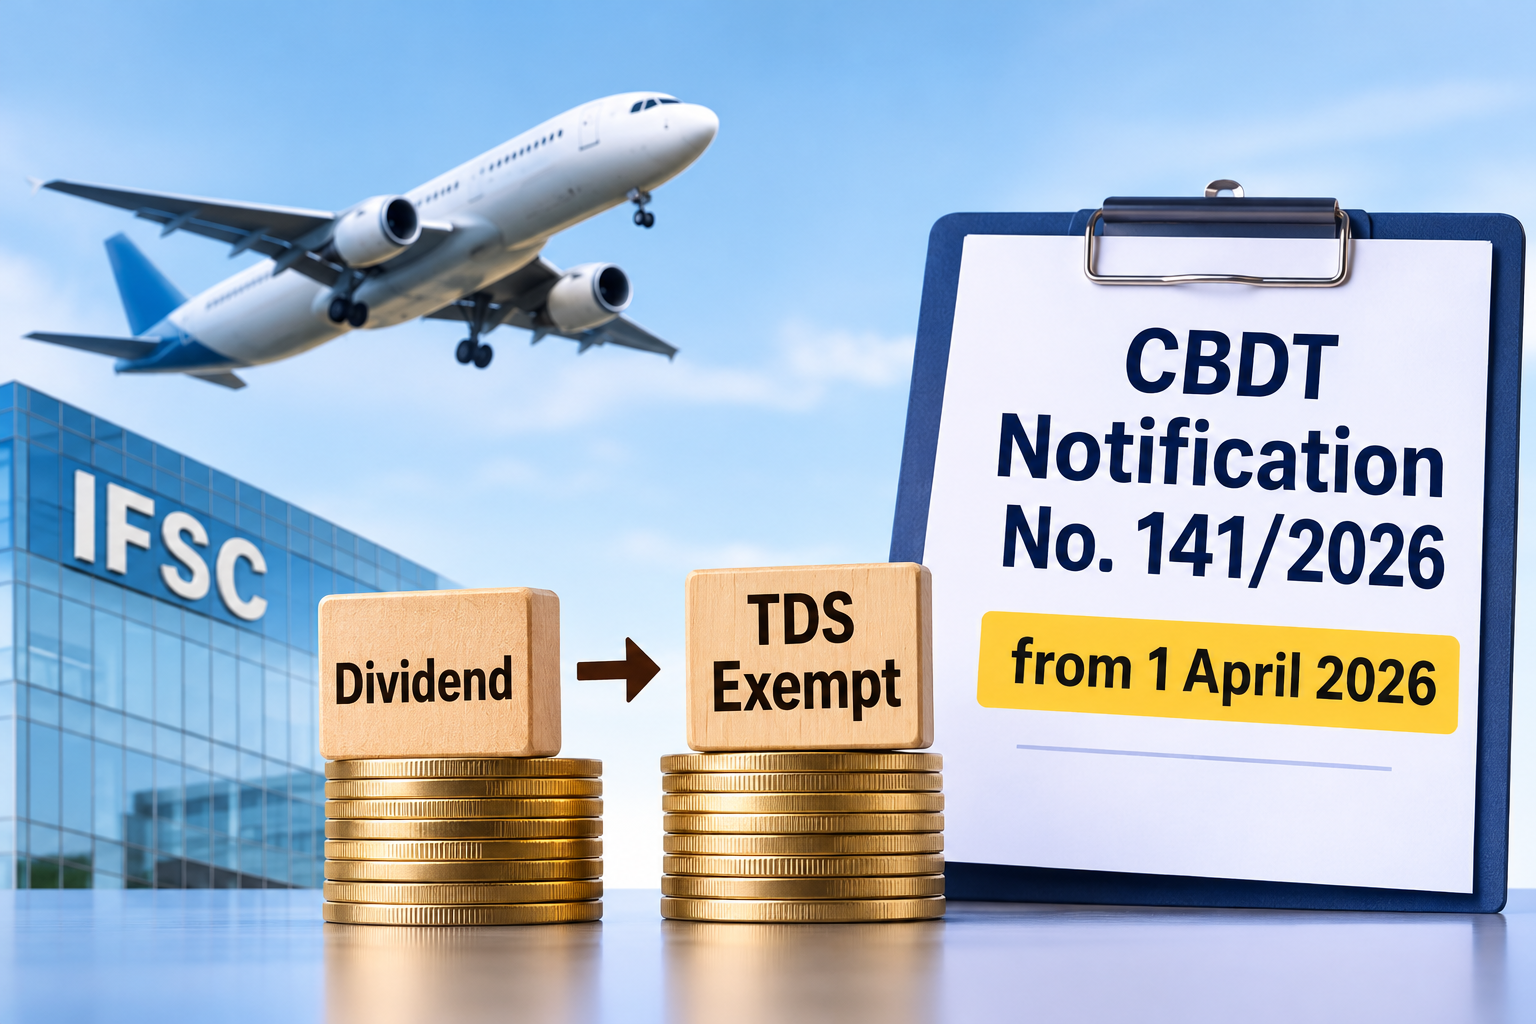
The Central Board of Direct Taxes (CBDT) has introduced an important tax compliance relief for eligible aircraft-leasing units operating within the International Financial Services Centre (IFSC). Through Notification No. 141/2026 dated 4 November 2026, CBDT has provided an exemption from Tax Deducted at Source (TDS) on specified dividend payments made by one eligible aircraft-leasing unit to another eligible aircraft-leasing unit situated in an IFSC.
This measure is expected to simplify tax compliance, improve operational efficiency and strengthen India’s position as an emerging international hub for aircraft leasing and aviation financing.
Understanding the TDS exemption
Generally, dividend payments attract TDS under the applicable provisions of the Income-tax Act, subject to the prescribed rates, conditions and exemptions.
However, the newly introduced exemption provides relief where dividend income is distributed by an eligible aircraft-leasing unit located in an IFSC to another eligible aircraft-leasing unit within an IFSC.
The objective is to facilitate the movement of dividend income between qualifying entities operating within the IFSC ecosystem without the additional procedural requirement of TDS deduction.
This exemption is particularly relevant for entities involved in aircraft leasing, aviation financing and related financial activities within India’s IFSC framework.
Key conditions for claiming the exemption
The exemption is not universally available to all companies operating in an IFSC. It is subject to fulfilment of specific eligibility and documentation requirements.
The important conditions include:
1. Eligible entities: Both the dividend-paying entity and the recipient entity must qualify as eligible aircraft-leasing units situated in an IFSC.
2. Prescribed declaration: The recipient aircraft-leasing unit must furnish the prescribed declaration in Form No. 1(N) to the dividend-paying entity.
3. Verification of eligibility: The dividend-paying entity should verify the prescribed eligibility conditions and maintain the relevant declaration and supporting documentation before applying the TDS exemption.
4. Effective date: The exemption is stated to be effective retrospectively from 1 April 2026, covering qualifying transactions falling within the applicable period.
Impact on businesses and tax professionals
The notification is an important development for the aviation leasing industry, particularly entities operating through the GIFT City IFSC ecosystem.
The exemption is expected to provide several practical benefits:
- Reduced compliance burden: Eligible entities will not be required to undertake TDS deduction and related deposit and reporting formalities for qualifying dividend payments.
- Improved cash flow: Dividend distributions can take place without the immediate withholding of tax, subject to the prescribed conditions.
- Simplified inter-company transactions: Eligible aircraft-leasing units can streamline dividend distribution arrangements within the IFSC framework.
- Enhanced investment environment: The measure may improve the attractiveness of India’s IFSC for international aircraft-leasing structures and financial transactions.
For Chartered Accountants and tax professionals, the notification creates an additional compliance checkpoint while advising IFSC-based clients. Professionals should examine the eligibility of both entities, verify the prescribed declaration and ensure that the exemption is applied only to qualifying dividend transactions.
Action points for tax practitioners
Businesses and their tax advisors should consider the following steps:
- Identify dividend payments made or proposed between eligible IFSC aircraft-leasing units from 1 April 2026.
- Verify the eligibility status of both the payer and recipient.
- Obtain and preserve Form No. 1(N) before applying the exemption.
- Review existing TDS processes and assess whether any corrective compliance action is required for transactions undertaken after the effective date.
- Maintain appropriate documentary evidence to support the non-deduction of TDS.
Conclusion
CBDT’s Notification No. 141/2026 represents a positive step towards creating a more efficient and business-friendly tax environment for India’s aircraft-leasing sector. By providing conditional TDS relief on dividend payments between eligible IFSC aircraft-leasing units, the Government has sought to reduce procedural complexities and facilitate financial transactions within the IFSC ecosystem.
While the exemption offers meaningful compliance relief, its benefits depend on strict adherence to the prescribed eligibility criteria and documentation requirements. Accordingly, businesses and tax professionals should carefully review the notification and incorporate the new provisions into their existing TDS compliance framework.
The notification reinforces India’s broader objective of positioning IFSC as a globally competitive centre for aviation financing and international financial services.