Proposed Centralised GST Administration to Simplify Compliance, Reduce Jurisdictional Issues and Improve Ease of Doing Business
New Delhi | 19 November 2026
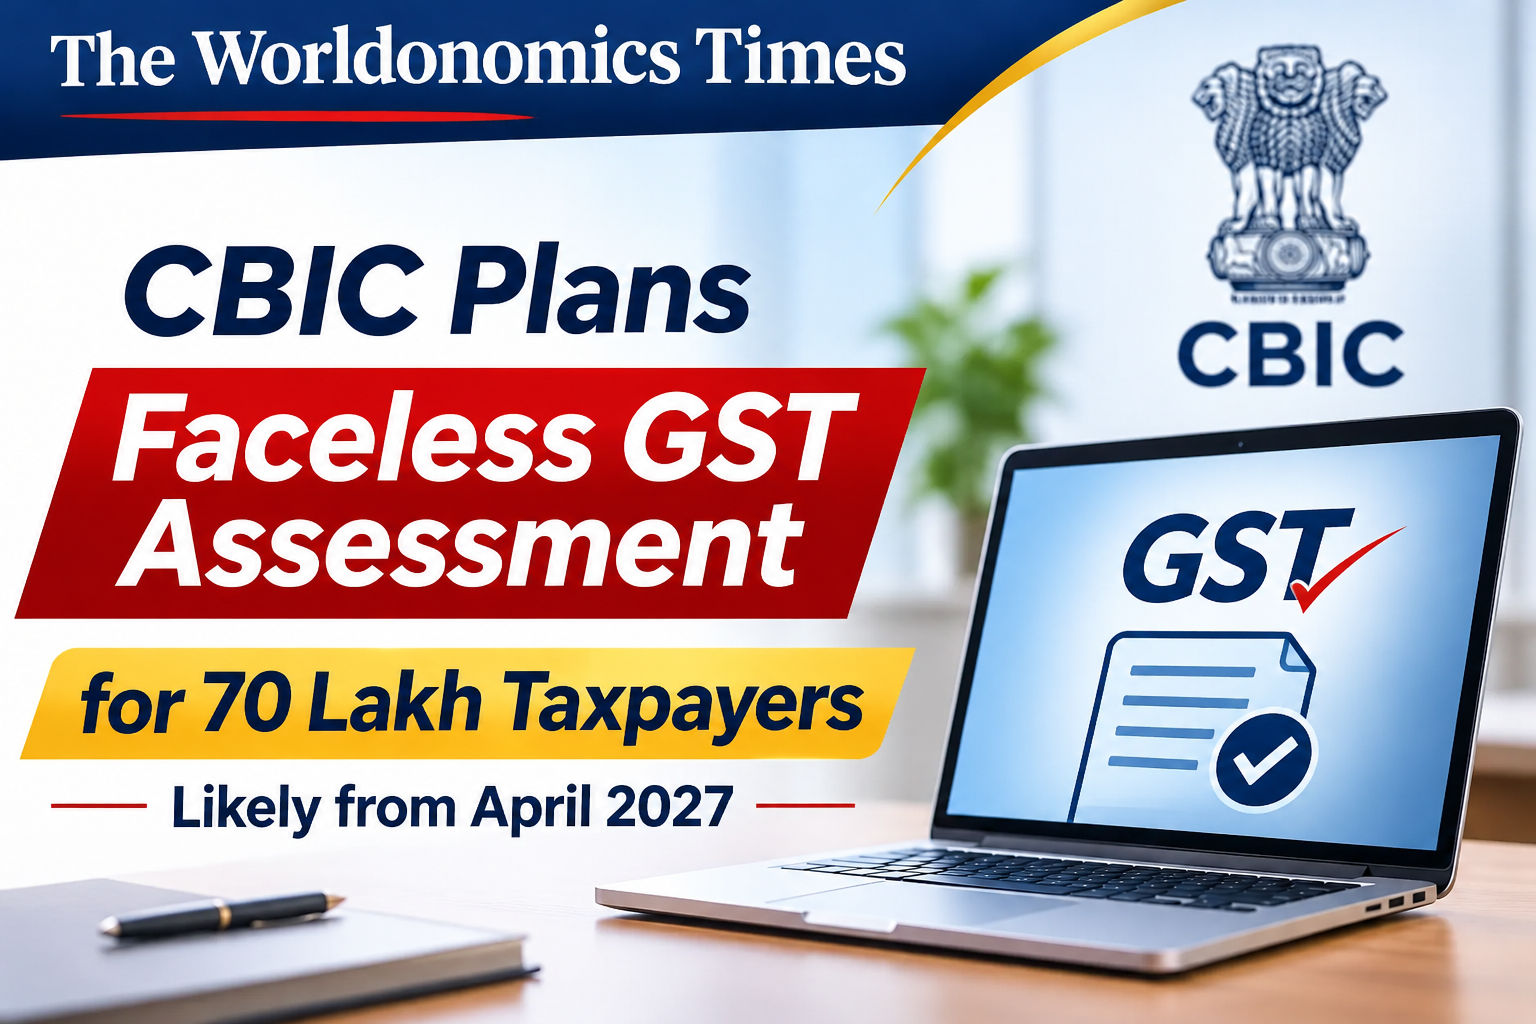
India’s Goods and Services Tax (GST) administration is set for another significant transformation, with the Central Board of Indirect Taxes and Customs (CBIC) preparing a new framework for faceless assessment and centralised administration of Central GST (CGST) taxpayers. The proposed initiative is expected to cover approximately 70 lakh taxpayers registered under the Central GST administration and is likely to be implemented from 1 April 2027.
CBIC Chairman Vivek Chaturvedi announced the development while addressing an industry conference organised by the PHD Chamber of Commerce and Industry (PHDCCI). He indicated that the draft framework would shortly be placed in the public domain for consultation with industry representatives and other stakeholders.
The proposed reforms aim to make GST administration more transparent, technology-driven and taxpayer-friendly while reducing the procedural difficulties faced by businesses operating across multiple jurisdictions.
Two Models of GST Administration
The proposed framework envisages two distinct administrative arrangements depending on the nature and scale of taxpayers.
1. Centralised Administration for Large Taxpayers
Large businesses operating through multiple GST registrations within a state or across different states are expected to benefit from a centralised administrative arrangement.
Under this proposed model, eligible large taxpayers would be able to approach a single physical office for various GST-related services, including:
- GST registration-related matters
- Scrutiny of GST returns
- Adjudication of tax disputes
- Review proceedings
- Appeals and related administrative matters
This arrangement is expected to reduce the difficulties faced by large corporate groups that currently interact with different tax jurisdictions for their GST-related requirements.
According to reports, approximately 2 lakh taxpayers have registrations across multiple CGST jurisdictions, either within the same state or across different states.
2. Faceless Assessment for Other Taxpayers
For other taxpayers, particularly smaller businesses and entrepreneurs operating within specific geographical areas, CBIC intends to introduce a faceless assessment system.
Under this approach, tax notices, hearings and orders are expected to be handled through a national digital platform rather than requiring taxpayers to interact physically with individual jurisdictional offices.
The proposed mechanism could significantly reduce physical visits to tax offices and make compliance processes more convenient for small businesses, startups, traders and service providers.
Why Is the Government Introducing This Reform?
India’s GST system operates through a combination of Central and State tax administrations. Although the digital GST infrastructure has improved compliance and return filing, businesses sometimes face administrative challenges arising from multiple registrations and jurisdictional arrangements.
Companies operating in several states may have to deal with different tax authorities for registration, scrutiny, adjudication and appeals.
The proposed centralised framework seeks to address these challenges by simplifying administrative interactions and introducing a more coordinated approach.
The initiative also reflects the government’s broader objective of moving towards a trust-based tax administration system.
Benefits for MSMEs and Large Businesses
The proposed reform could offer several advantages to the Indian business ecosystem.
Reduced Compliance Burden: Faceless procedures may reduce the need for physical visits and repeated interactions with tax authorities.
Greater Administrative Consistency: A common framework could encourage more uniform procedures in scrutiny, assessment and adjudication.
Ease of Doing Business: Large corporate groups may benefit from a single administrative point of contact for multiple GST registrations.
Technology-Driven Governance: Digital notices, hearings and orders could improve communication, record management and procedural efficiency.
Better Support for MSMEs: Smaller businesses may benefit from a simplified digital interface and reduced dependence on physical administrative processes.
What Should CA, CMA and CS Professionals Know?
The proposed framework is particularly relevant for Chartered Accountants, Cost Accountants, Company Secretaries, GST practitioners and corporate finance professionals.
Professionals advising businesses on GST compliance should closely monitor the proposed framework and assess its implications for existing compliance arrangements.
Businesses may need to review their internal GST documentation, authorisation processes, response mechanisms for departmental notices and digital record-management systems.
Tax professionals should also examine the proposed procedures for virtual hearings, jurisdictional allocation, adjudication and appeals once the draft becomes available.
Importantly, the proposed system should ensure that taxpayers retain adequate opportunities to present their cases, submit supporting documents and obtain reasoned orders in accordance with applicable legal provisions.
Public Consultation Before Implementation
CBIC Chairman Vivek Chaturvedi has indicated that the proposed framework will be released for public and stakeholder consultation shortly.
Industry associations, business organisations, tax practitioners and professional institutions will have an opportunity to examine the proposal and provide suggestions before its implementation.
The consultation process will be important in addressing practical concerns, particularly regarding the transition from existing jurisdiction-based arrangements to the proposed centralised and faceless mechanisms.
The framework is expected to be introduced from the beginning of the financial year 2027-28, subject to the finalisation of the proposal and necessary administrative arrangements.
A New Chapter in India’s GST Administration
The proposed faceless and centralised GST administration framework represents an important step in the continuing evolution of India’s indirect tax system.
While earlier GST reforms focused significantly on rate rationalisation, digital return filing and e-invoicing, the proposed initiative places greater emphasis on improving the administrative experience of taxpayers.
If implemented effectively, the reform could reduce jurisdictional complexities, improve consistency in tax administration and strengthen confidence between businesses and tax authorities.
For India’s approximately 70 lakh CGST-registered taxpayers, the proposed framework could mark a meaningful shift towards a more accessible, efficient and technology-enabled tax administration system.
The Worldonomics Times
Business | Economy | Finance | Taxation | Governance