Rising trade barriers, geopolitical tensions and shifting government policies are reshaping international commerce, forcing businesses to reconsider supply chains, explore new markets and prepare for a more unpredictable global trading environment.
International trade remains a major driver of global economic growth, connecting businesses, consumers and industries across national borders. However, the global trading system is facing renewed uncertainty as trade tensions, changing tariff policies, geopolitical competition and regulatory differences create fresh challenges for exporters and importers.
Governments are increasingly prioritising domestic industries, national security and strategic economic interests when making trade policy decisions. While these measures are often intended to protect local businesses and strengthen economic independence, they can also increase costs, disrupt established supply chains and create uncertainty for international companies.
The World Trade Organization (WTO), in its World Trade Report 2026, has highlighted significant pressure on the rules-based multilateral trading system. Its assessment points to geopolitical tensions, government interventions and changing patterns of global production as major challenges for international trade.
Trade Tensions Reshape International Business
One of the biggest challenges facing global trade is the growing use of tariffs and other trade restrictions.
Countries are increasingly using import duties, export controls, subsidies and regulatory measures to protect domestic industries or strengthen their position in strategically important sectors.
These policies can affect industries ranging from automobiles and steel to semiconductors, agricultural products and advanced technologies.
For exporters, higher tariffs can make products more expensive in overseas markets and reduce their competitiveness. Importers, meanwhile, may face increased procurement costs, fewer supplier options and difficulties maintaining stable prices.
Uncertainty surrounding future trade policies can be equally damaging. Businesses planning international investments or long-term supply agreements need predictable rules to calculate costs and manage commercial risks.
When trade regulations change frequently, companies may delay expansion plans or reconsider the markets in which they operate.
Supply Chains Under Pressure
Global supply chains have become increasingly interconnected, with raw materials, components and finished products often crossing several international borders before reaching consumers.
Although this system has improved efficiency and reduced production costs, it has also created vulnerabilities when geopolitical disputes, transportation disruptions or policy changes affect key trading routes.
Businesses are therefore moving beyond traditional cost-focused sourcing strategies and placing greater importance on supply-chain resilience.
Many companies are diversifying suppliers, exploring alternative manufacturing locations and increasing regional sourcing to reduce dependence on a limited number of countries.
This trend, often described through strategies such as nearshoring and friendshoring, is gradually changing the geography of international production.
However, building alternative supply networks requires investment, new business partnerships and time. Companies may also face higher costs when shifting production away from established manufacturing centres.
WTO Warns of Growing Trade Fragmentation
The WTO’s World Trade Report 2026 identifies geopolitical tensions and differences in national economic policies as important pressures on international trade cooperation.
The report warns that a fragmented global trading system could carry substantial economic costs. In a scenario where the world economy divides into geopolitically aligned blocs, WTO modelling estimates that global GDP could decline by 5.1% and global exports by 18.6% compared with its baseline.
These figures represent a potential scenario rather than a forecast of what will necessarily happen.
The concern is that excessive fragmentation could weaken the benefits of international specialisation, reduce market access and make cross-border business more expensive.
A predictable and transparent trading environment remains particularly important for smaller economies, which often have less bargaining power when negotiating with larger trading partners.
Exporters and Importers Face Rising Business Risks
Changing trade policies are creating practical difficulties for businesses of every size.
Exporters must monitor tariff changes, product standards, customs procedures and documentation requirements across different markets. Even a small regulatory change can affect delivery schedules, profit margins and contractual obligations.
Importers face similar challenges. Changes in duties, restrictions on particular products and delays at international ports can increase the cost of raw materials and finished goods.
Small and medium-sized enterprises are especially vulnerable because they often have limited financial resources and fewer alternative suppliers than multinational corporations.
To manage these risks, businesses are investing in better trade compliance systems, market research, supplier diversification and more flexible procurement arrangements.
Developing Economies Face Both Risks and Opportunities
Developing economies face a complex situation as global trade relationships evolve.
Countries that depend heavily on exports to a small number of markets may experience difficulties when tariffs increase or demand weakens. Those reliant on imported fuel, machinery, technology and industrial components can also face higher production expenses.
However, changing supply chains may create opportunities for emerging manufacturing centres.
Countries with competitive production costs, reliable infrastructure, skilled workers and stable economic policies can attract investment from companies seeking alternative production locations.
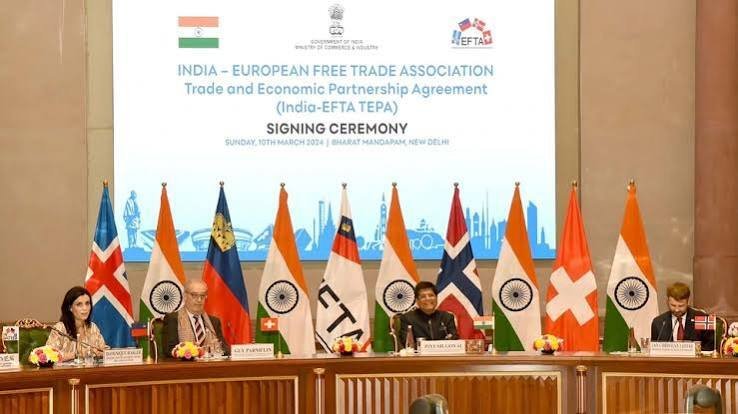
India, for example, has opportunities to strengthen its role in global manufacturing and services through infrastructure development, export diversification and improved logistics.
Sectors such as electronics, pharmaceuticals, engineering goods, textiles and information technology could benefit from new international partnerships.
Nevertheless, long-term success will depend on consistent policies, competitive production standards and the ability to meet international quality and regulatory requirements.
Technology and Digital Trade Transform Global Commerce
Technology is creating new opportunities even as traditional trade faces uncertainty.
Artificial intelligence, digital platforms, electronic payments and advanced logistics systems are changing how companies conduct international business.
The WTO’s October 2026 trade outlook noted that strong investment in AI-related infrastructure helped support merchandise trade growth during the first half of the year. Its revised forecast projected merchandise trade volume growth of 3.9% in 2026, compared with the earlier March forecast of 1.9%.
This demonstrates that global trade can remain resilient despite political and economic challenges. However, the benefits are uneven across regions and sectors.
Digital trade also faces emerging regulatory questions involving data protection, cybersecurity, cross-border data flows and technology controls. Greater international coordination will be necessary to ensure that digital commerce remains accessible and competitive.
The Worldonomics Times View
Global trade is entering a period in which economic decisions are increasingly influenced by geopolitical priorities, national security concerns and domestic industrial strategies.
In our view, the biggest risk is not simply the introduction of higher tariffs or individual trade restrictions. It is the gradual erosion of predictability and trust that businesses need to operate across international markets.
Trade protection may provide temporary support to selected domestic industries, but excessive restrictions can increase costs for consumers, weaken competition and disrupt production networks.
We believe governments should focus on creating a balance between protecting legitimate national interests and maintaining open, transparent and rules-based international commerce.
For India and other emerging economies, this changing environment offers an opportunity to attract investment, expand manufacturing capabilities and build stronger export relationships. However, achieving these goals will require reliable infrastructure, efficient customs systems, consistent regulations and greater support for small exporters.
Businesses must also prepare for a more complex trading environment by diversifying markets, strengthening supplier relationships and adopting technology-driven trade management systems.
Our position is clear: global trade needs cooperation, not excessive fragmentation. Countries that maintain constructive international partnerships while strengthening domestic competitiveness will be better positioned to manage uncertainty.
The future of international commerce will depend not only on how much countries trade, but also on how effectively they cooperate to keep markets accessible, supply chains resilient and economic opportunities widely shared.