The Worldonomics Times | Banking, Finance & Capital Markets | 4 November 2026
SEBI Enforcement Action
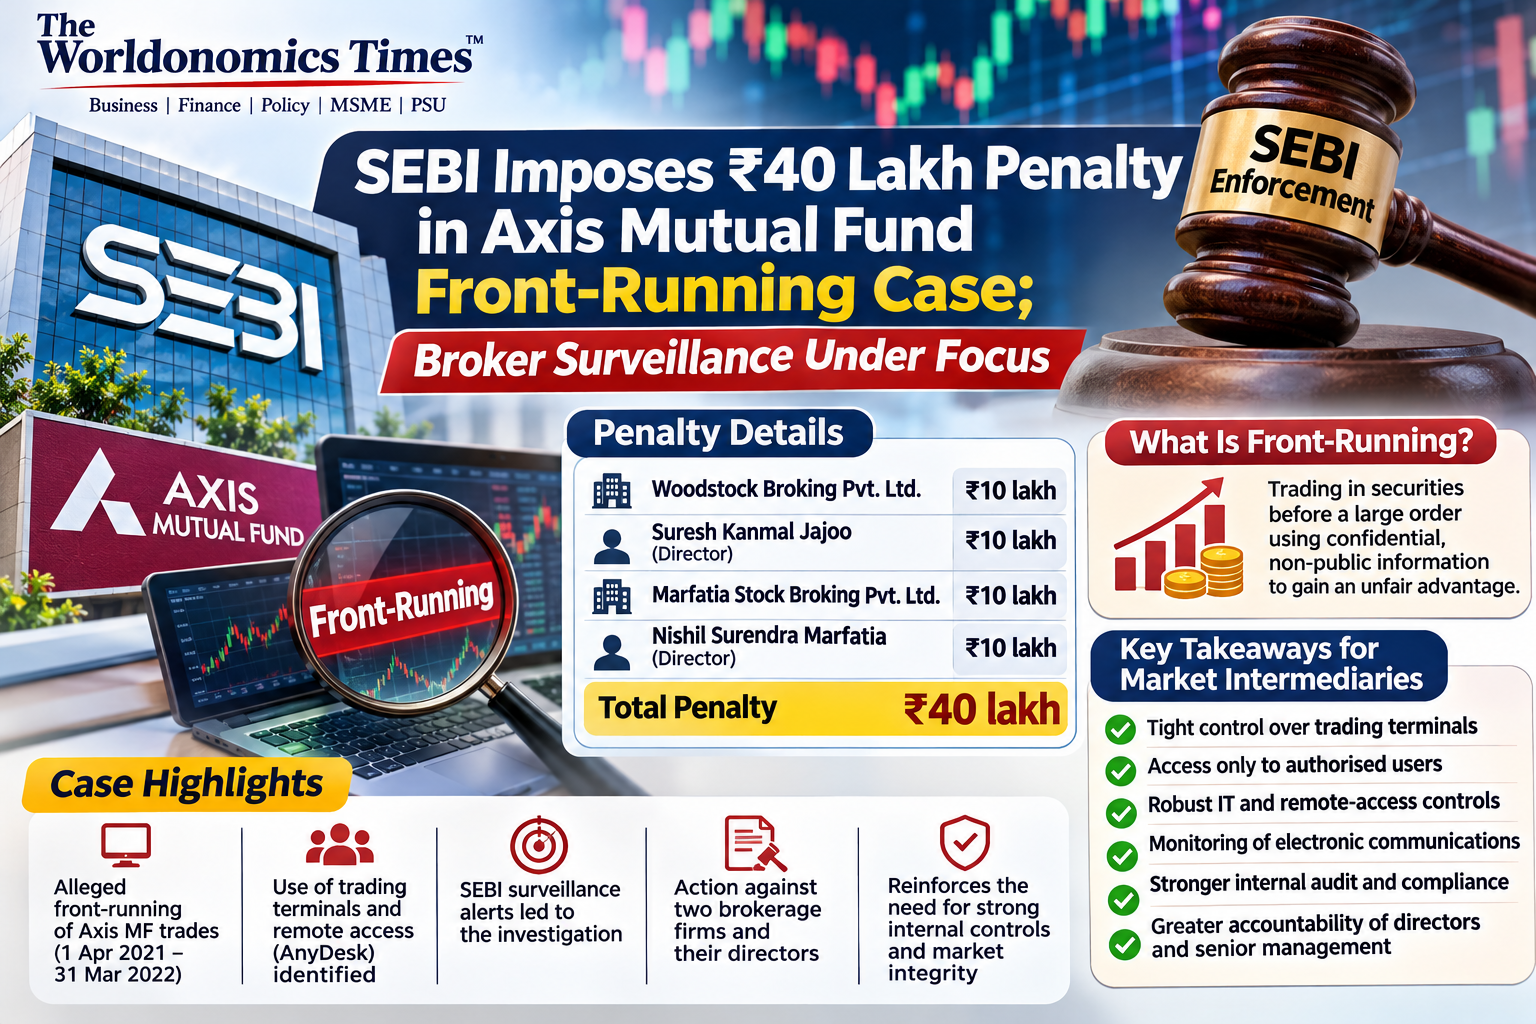
The Securities and Exchange Board of India (SEBI) has imposed a total penalty of ₹40 lakh on two stockbroking firms and their directors for allegedly facilitating front-running trades involving Axis Mutual Fund. The regulatory action highlights the importance of maintaining strict controls over trading terminals, authorised user access, IT infrastructure and internal compliance systems in the securities market.
In an adjudication order dated 3 November 2026, SEBI imposed penalties of ₹10 lakh each on Woodstock Broking Private Limited, its director Suresh Kanmal Jajoo, Marfatia Stock Broking Private Limited and its director Nishil Surendra Marfatia. Moneycontrol+1
The case relates to alleged front-running activity involving trades executed by Axis Mutual Fund during the period from 1 April 2021 to 31 March 2022. The investigation was initiated following alerts generated by SEBI’s market surveillance system, which indicated possible front-running of transactions undertaken by the mutual fund.
What Is Front-Running?
Front-running refers to trading in securities ahead of a large anticipated transaction by using confidential, non-public information about that transaction to gain an unfair market advantage.
For example, if an individual obtains advance information that a large mutual fund is planning to purchase a particular stock, that individual may buy the stock before the fund executes its order. The subsequent market movement following the institutional transaction may allow the individual to benefit from the price impact.
Such practices undermine market integrity, create an unfair advantage and can adversely affect investor confidence.
SEBI’s regulatory framework prohibits fraudulent and unfair trade practices in securities markets, including activities that compromise fair and transparent price discovery.
How the Alleged Trading Arrangement Operated
According to SEBI’s findings reported in connection with the adjudication order, the two brokerage firms facilitated the installation and operation of their ODIN trading terminals on computer systems used by Prijesh Kurani, who was operating from Dubai.
Kurani was neither an authorised person nor a registered dealer of the concerned brokerage firms. The investigation identified the use of AnyDesk, a remote-access application, in facilitating the operation of the trading software.
The investigation also identified Viresh Joshi, who was then serving as the chief dealer at Axis Mutual Fund, as the alleged source of information about the fund’s impending trades. The Economic Times+1
SEBI examined the role of several individuals and intermediaries in the alleged arrangement, including persons who provided information, executed trades and facilitated the operational infrastructure.
The investigation relied on different forms of evidence, including electronic communications, technical information relating to computer systems and details concerning access to trading terminals.
Why SEBI Penalised the Brokerage Firms
SEBI’s investigation focused on the responsibility of registered stockbrokers to maintain effective control over their trading infrastructure and ensure that access is provided only to authorised individuals.
The regulator examined the role of both brokerage firms and their directors in facilitating the alleged arrangement.
In the case of Woodstock Broking, SEBI considered evidence relating to trading-account arrangements, WhatsApp communications, technical details and the involvement of personnel in enabling remote access.
In the case of Marfatia Stock Broking, the regulator examined the role of its IT personnel, communications and technical evidence linking computer systems used in the transactions.
SEBI concluded that the conduct of the concerned entities went beyond a mere technical or administrative lapse and involved facilitation of the trading arrangement. Moneycontrol+1
Penalty Details: Four Entities Face ₹40 Lakh in Fines
The penalties imposed by SEBI are summarised below:
| Entity | Penalty |
|---|---|
| Woodstock Broking Pvt. Ltd. | ₹10 lakh |
| Suresh Kanmal Jajoo | ₹10 lakh |
| Marfatia Stock Broking Pvt. Ltd. | ₹10 lakh |
| Nishil Surendra Marfatia | ₹10 lakh |
| Total | ₹40 lakh |
The adjudication proceedings against six other noticees were disposed of without monetary penalties in this particular order. The four penalised entities were directed to pay the penalties within 45 days of receiving the order. Moneycontrol+1
Implications for Stockbrokers and Compliance Professionals
The SEBI action carries important lessons for stockbroking firms, compliance officers, internal auditors, IT administrators and finance professionals.
Some key areas requiring attention include:
1. Stronger control over trading terminals
Brokerage firms must ensure that trading terminals are operated only by authorised users. Sharing credentials, allowing unauthorised remote access or permitting third-party operation can create significant regulatory risks.
2. Effective IT access management
Firms should maintain documented access policies, user authentication mechanisms, remote-access controls and regular reviews of trading infrastructure.
3. Monitoring of electronic communications
Communication records, access logs and system-level information can play an important role in identifying suspicious activities and establishing accountability.
4. Strengthening internal audit systems
Internal audit teams should periodically examine trading-terminal access, user permissions, client-account operations and compliance with regulatory requirements.
5. Accountability of directors and senior management
The case highlights that regulatory scrutiny may extend beyond the brokerage entity to individuals whose active involvement in the relevant arrangements is established.
Importance of Market Surveillance in Preventing Unfair Trading
The case also demonstrates the role of technology-driven surveillance in identifying unusual trading patterns.
SEBI’s surveillance systems generated alerts that led to the investigation into suspected front-running of Axis Mutual Fund transactions.
With increasing volumes of electronic trading, market surveillance has become an important component of securities-market regulation. Data analytics, transaction monitoring, digital evidence and technological audit trails can help regulators identify suspicious trading activity.
For market intermediaries, this reinforces the need to maintain robust systems capable of detecting and preventing unauthorised trading activities.
A Compliance Lesson for India’s Securities Market
India’s securities market depends on investor confidence, transparent price discovery and fair access to market infrastructure. Stockbrokers and other intermediaries play a critical role in maintaining these standards.
The ₹40 lakh penalty in the Axis Mutual Fund front-running matter sends an important regulatory message regarding the responsibilities of registered brokers. Trading infrastructure cannot be treated merely as a technological facility; it must remain under proper operational, supervisory and compliance control.
For CA, CMA, CS and other finance professionals working in brokerage firms, mutual funds, financial institutions and compliance functions, the case provides a practical example of the importance of internal controls, IT governance, risk management and regulatory accountability.
As India’s capital markets continue to expand, stronger compliance frameworks and effective surveillance mechanisms will remain essential to protecting investors and maintaining market integrity.
The Worldonomics Times | Banking, Finance & Capital Markets