Proposed changes could reduce the tax burden on foreign portfolio investors and give domestic mutual fund investors greater flexibility to switch schemes
New Delhi | 4 November 2026
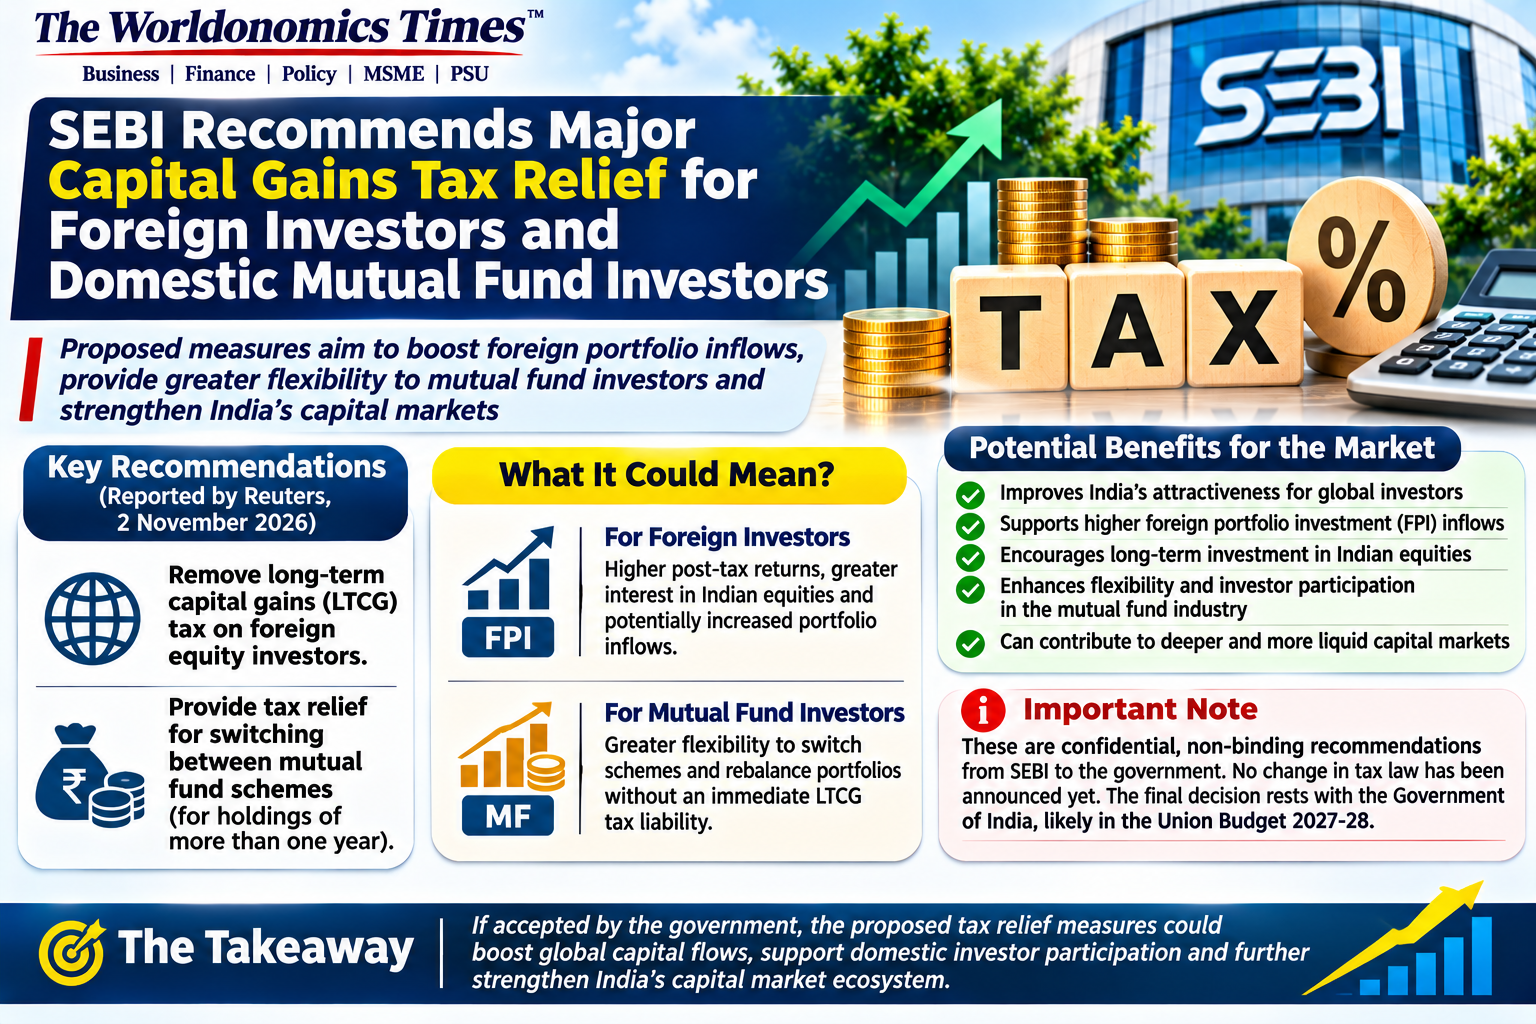
The Securities and Exchange Board of India (SEBI) has reportedly recommended a series of capital gains tax relief measures to the Central Government, including the removal of long-term capital gains (LTCG) tax on foreign equity investors and tax relief for domestic mutual fund investors switching between schemes. If accepted, the proposals could influence foreign portfolio investment flows, domestic mutual fund participation and the overall competitiveness of India’s capital markets.
The recommendations were reported by Reuters on 2 November 2026, citing two sources familiar with the matter. The proposals form part of SEBI’s confidential pre-Budget representations to the government ahead of the Union Budget 2027-28. They are advisory and non-binding in nature. No change in the tax law has been announced, and the final decision rests with the Central Government. <Link ref=”turn151427news15″ title=”Reuters report”/>.
SEBI proposes removal of LTCG tax for foreign investors
One of the major recommendations is to remove the long-term capital gains tax applicable to foreign investors on eligible equity investments in India.
Under the current tax framework, eligible long-term gains on listed equity securities are generally subject to a 12.5% tax, subject to applicable conditions and exemptions. Short-term capital gains on specified equity transactions are generally taxed at 20%. Foreign investors also bear securities transaction tax (STT) on applicable trades and withholding taxes on dividend income.
SEBI’s reported recommendation seeks to reduce this tax burden and improve the post-tax returns available to foreign investors. The proposal comes at a time when overseas investors have raised concerns about the cost of investing in Indian equities and the competitiveness of India’s tax framework compared with other markets.
According to Reuters, foreign investors have sold a record approximately $31 billion worth of Indian stocks during 2026. The report also highlighted the relative underperformance of Indian equities against several emerging-market benchmarks over the preceding two years. <Link ref=”turn151427news15″ title=”Reuters market report”/>.
Tax relief proposed for domestic mutual fund switches
The second recommendation concerns domestic mutual fund investors.
SEBI has reportedly suggested that switching from one mutual fund scheme to another should not be treated as a taxable sale for long-term holdings held for more than one year. The proposal is intended to give investors greater flexibility to realign their portfolios without an immediate long-term capital gains tax liability.
At present, switching between mutual fund schemes generally involves redemption of units from the existing scheme and investment in another scheme. This transaction is ordinarily treated as a transfer for capital gains tax purposes. Consequently, an investor may incur a tax liability even when the money is being reinvested in another mutual fund scheme rather than withdrawn from the market.
If the proposal is accepted and implemented, eligible investors could be able to move between schemes with fewer immediate tax consequences. This may help investors adjust their asset allocation, respond to changing financial goals and review their investment strategies without the same tax friction.
The recommendation is particularly relevant given the scale of India’s mutual fund industry. Reuters reported that domestic mutual funds manage assets of approximately ₹82.6 trillion, with significant regular contributions through systematic investment plans and other monthly investment channels. <Link ref=”turn151427news15″ title=”Reuters report on mutual fund assets”/>.
Why SEBI is considering these measures
The reported recommendations reflect concerns about the cost of investing in Indian equity markets. SEBI has reportedly highlighted that transaction costs associated with equity investment in India are high compared with several other jurisdictions.
Over the last two years, the regulator has held multiple interactions with foreign investors. Taxation has reportedly emerged as a recurring concern during these discussions.
Foreign portfolio investors consider several factors before allocating capital to a market, including taxation, transaction costs, currency movements, market liquidity, regulatory certainty and expected returns. A reduction in capital gains tax could improve the post-tax return calculation for overseas investors.
For domestic investors, the mutual fund switching proposal addresses a different concern: the tax implications of changing investment schemes. It could provide greater flexibility to investors who wish to remain within the mutual fund ecosystem while adjusting their portfolios.
Potential impact on foreign portfolio investment
If the government accepts the proposal to remove LTCG tax for foreign equity investors, India could become more competitive from a post-tax investment perspective.
The potential benefits may include:
- Improved post-tax returns on eligible long-term equity investments.
- Greater interest from foreign portfolio investors.
- Improved competitiveness against other emerging markets.
- Potential support for portfolio inflows and market liquidity.
- A more favourable environment for long-term foreign capital allocation.
However, tax relief alone may not determine foreign investment decisions. Global interest rates, geopolitical developments, corporate earnings, currency stability, valuations and India’s economic outlook will continue to influence investment flows.
Therefore, any improvement in foreign inflows would depend on the broader investment environment and the final design of the policy, if approved.
Implications for India’s mutual fund industry
The proposed relief for mutual fund switches could also have implications for asset management companies, distributors and individual investors.
Investors often need to change schemes because of portfolio rebalancing, changes in risk appetite, investment objectives or fund performance. If a qualifying switch can be made without triggering an immediate LTCG tax liability, it may encourage investors to make portfolio adjustments while keeping their capital invested in domestic mutual funds.
For asset management companies, the proposal could support investor retention and facilitate movement of funds between schemes. However, the final treatment would depend on the eligibility conditions, holding-period requirements and operational rules adopted by the government.
Government decision will be crucial
Both recommendations are still at the proposal stage. They are part of SEBI’s reported pre-Budget submissions and do not represent an approved change in India’s tax policy.
The Ministry of Finance and the Central Government will decide whether to accept, modify or reject the suggestions. Any approved tax relief would require appropriate changes to the applicable legal and tax framework.
Until an official announcement and implementation, investors must continue to follow the existing capital gains tax provisions. The reported recommendations should not be treated as an immediate tax exemption or as a basis for changing investment decisions.
A significant policy discussion for India’s capital markets
SEBI’s reported proposals bring two important issues into focus: India’s ability to attract foreign equity capital and the need to encourage long-term participation by domestic investors.
Removing LTCG tax for foreign equity investors could address one of the concerns raised by overseas market participants, while tax relief on eligible mutual fund switches could offer domestic investors greater flexibility.
The proposals also highlight the wider role of tax policy in shaping investment behaviour and capital-market development. Their eventual impact will depend on the government’s decision, the scope of any exemptions and the safeguards included in the final framework.
For now, the recommendations mark an important policy discussion ahead of the Union Budget 2027-28. Market participants will be watching closely to see whether the government translates any of these suggestions into concrete tax reforms.